Being Deployed? Here Is What You Need to Do

Being Deployed? Here Is What You Need to Do

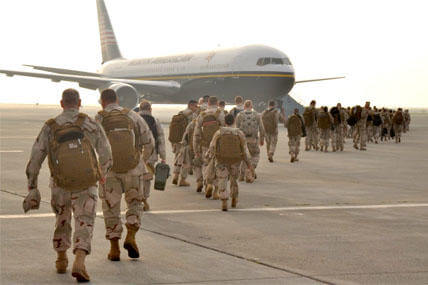
You have just received your orders, and you will be deployed shortly. No matter how soon you are leaving, there is still time to ensure that your affairs are in order.

  1. Review or prepare a Family Care Plan. Regardless of the branch of the military in which you are serving, you may be required to complete a Family Care Plan (FCP). An FCP is usually required for individuals who
    • are single parents with custody of children under 19,
    • are in dual-military marriages with dependent children,
    • are married and have custody or joint custody of a child whose other legal parent is not their current spouse,
    • bear sole responsibility for the care of children under 19 or for others who are unable to care for themselves in the service member’s absence, or
    • are primarily responsible for the care of a dependent family member.

      An FCP provides written instructions and legal documentation outlining how your loved ones’ day-to-day needs will be met in your absence. It designates a caregiver, confirms their willingness to take on that responsibility, and includes essential documents such as powers of attorney and medical authorizations. You will need to submit this plan to your command for review and approval to ensure that everything is in place and meets applicable military requirements.
  2. Review estate planning documents or have them prepared. To ensure that your wishes are carried out, they must be written down in a legally valid way. You can accomplish this through the use of a last will and testament (sometimes referred to as a will) or a revocable living trust (sometimes referred to as a trust). If you already have a will or trust, make sure that it still accurately reflects your current wishes. Also, if you have married or had a child since your will was prepared, you may want to consider revising your plan to include a trust. While a will and a trust are both designed to distribute your money and property according to your wishes, a trust has the added benefit of allowing the administration to take place without court involvement, which can save time and money and maintain your loved ones’ privacy. A trust also can be designed to protect your beneficiaries’ inheritances from creditors, predators, judgments, or divorcing spouses.

    If you decide to transition from a will-based estate plan to a trust-based plan, you will still need a pour-over will as part of your overall estate plan. Even with a trust handling the distribution of your assets, a will serves several important functions; most notably, it allows you to nominate a guardian for your minor children if something happens to you. A will can also serve as a safety net by directing any assets not already titled in the name of your trust (or otherwise passed by beneficiary designation) to be “poured over” into the trust upon your death. 

    While both a will and a trust play an important role in securing your loved ones’ financial future, there are other estate planning tools that need to be reviewed or created to ensure maximum protection for you and your loved ones.

    Financial Power of Attorney

    If your spouse or you are going to be deployed, having a financial power of attorney is incredibly important. This tool allows you to appoint a trusted individual to act as your agent for financial and legal tasks. This person will be able to transact business on your behalf. This tool can be customized to fit your unique situation and circumstances.

    Medical Power of Attorney

    This tool allows you to name someone to make medical decisions on your behalf if you are unable to make or communicate those decisions yourself.

    Power of Attorney for Minor Children

    Some states recognize a tool that allows you and your spouse to give a named person the authority to make decisions on behalf of your minor child. This can be helpful if one parent is deployed and the other parent is unreachable or if your minor child is spending time away from you. The length of time this tool is effective after it is signed varies by state. Also, in most states, the named person cannot consent to the adoption or marriage of your minor child.

    Separate Nomination of Guardian

    Depending on whether it is permitted in your state, you may want to consider creating a separate document to nominate guardians for your minor children. Many people prefer this approach because it is typically easier and less expensive to update than a last will and testament. In addition, this separate document may carry more legal weight in the selection of a guardian for your minor children if you are alive but become unable to care for them, unlike a last will and testament, which takes effect only upon your death.
  3. Review or complete beneficiary designations. As a service member, you may have access to life insurance policies or other survivor benefits through the military. Review these policies and any corresponding beneficiary designations to ensure that they still reflect your current wishes and that the right person will receive the benefits. As mentioned, this is especially important if you have recently married or had children. Although it is common to name loved ones as the beneficiaries of a life insurance policy, if the people you named are minor children who may need assistance managing the large lump-sum distribution of the policy or benefits, you should consider creating a trust and naming the trust as the beneficiary instead. Your loved ones will still receive the benefit of the death proceeds, but you will have the ability to provide instructions as to how the money is to be used rather than permitting an outright distribution. You will also have the ability to choose who will oversee the trust.
  1. Assess your life insurance needs. When planning for the financial security of your family, assessing their specific needs is important. According to the United States Department of Veterans Affairs, Servicemembers’ Group Life Insurance is available in $50,000 increments up to a maximum of $500,000. However, if you need more coverage than this, research your other options as early as possible. We would be happy to provide you with the names of a few trusted agents who can discuss your options based on your unique circumstances.

We Are Here to Help

You have made a heroic decision to serve your country, and we are here to serve you. If you have any questions about starting or reviewing your estate plan, please call us.

Do You Go By Different Names? Ensure That Your Estate Planning Attorney Knows

Do You Go By Different Names? Ensure That Your Estate Planning Attorney Knows

What is in a name?

If you are a beneficiary or a creditor of an estate, or if you are setting up an estate plan, your name means a great deal.

It is not unusual for a person to go by different names, such as the name we are given at birth and the names we choose for ourselves. Some of us use nicknames; others use our middle name or initials as our primary name. We may also legally change our name due to marriage, divorce, gender identity, or personal preference. Some people even use different names within specific communities and groups.

However you choose to identify yourself and whether you have changed your name formally or informally—in the eyes of the court or just among friends and family—you need to ensure that any different names, and variations thereof, are reconciled across legal documents, including your estate plan, to avoid confusion and unintended outcomes.

Same Person, Different Name: Name Variations Are Common

Your name is a seemingly simple detail that may not receive much attention in your daily life, but it can have major ramifications for your estate plan and what happens after you pass.

Think for a moment about how you present yourself on paper and in person. The following are some examples of common name variations:

  • Full legal name (first, middle, last). Some people consistently use their full legal name (e.g., Katherine Elizabeth Johnson).
  • Middle initial (first, middle initial, last). Others prefer a more concise version (e.g., Katherine E. Johnson).
  • Middle name instead of first (middle, last). In some cases, someone may go by their middle name (e.g., Elizabeth Johnson) instead of their legal first name (Katherine).
  • Nickname. Nicknames can differ significantly from legal names (e.g., Kate for Katherine, Jack for John, or Peg for Margaret).

The names you use, like the clothes you wear, may have changed over the years to reflect how you have changed. Most adults likely have at least one alternate name (particularly women, due to marriage), but nongiven names can also appear in other contexts.

  • Maiden names. According to Pew Research, nearly 80 percent of US women and 5 percent of US men in opposite-sex marriages take their spouse’s surname after marriage,[1] while around 14 percent of women in opposite-sex marriages retain their maiden name.[2]
  • Hyphenated last names. An estimated 20 percent of married couples in North America use hyphenated last names.[3] However, if parents pass their hyphenated last name to their children, the children may later drop the hyphen. As NPR notes, merging hyphenated names can become a “bureaucratic nightmare,” causing confusion at schools, at doctors’ offices, and in other settings.[4]
  • Online aliases and pseudonyms. A study from blog comment hosting service Disqus found that 70 percent of people who use nicknames or aliases online do so for privacy.[5]
  • Professional names. Authors and entertainers often use pseudonyms, such as J.K. Rowling writing as Robert Galbraith, Robert Zimmerman performing as Bob Dylan, or Prince using a symbol instead of a name. People may also use an alias to separate their personal and professional identities.
  • Cultural practices. Immigrants may Americanize their names as part of the assimilation process and for economic benefits, especially if their legal name is difficult to spell or pronounce. Around one-third of immigrants to the United States changed their names within 10 years of their arrival.[6]
  • Adoption. For people who are adopted, both their first and last names can be changed once the process is complete.
  • Personal choice. Many celebrities, including Angelina Jolie, Cher, and Elton John, have legally changed their names.

Why Name Nuances Matter in Your Estate Plan

Variations in how you identify yourself might seem trivial in everyday contexts and conversations, but they can create issues in your estate plan. Informing your attorney about every name you have used can prevent headaches and potential complications. Here is how:

  • Identifying what you own. Estate planning begins with cataloging assets (e.g., bank accounts, real estate, investments, and digital assets). Tracking and inventorying these assets can be challenging if you have used different names. For example, a bank account under the name Katherine E. Johnson and a home under Elizabeth Johnson might be missed if only one name is listed. The deed to your house, brokerage accounts, and vehicle titles should also be checked for name variances. Without knowing all the nuances of your name, your attorney might inadvertently overlook assets when creating your estate plan, leading to certain assets not being included in your plan and delays and legal hurdles for your beneficiaries, who may need to provide legal documentation of your name change.
  • Putting creditors on notice. The person you choose to wind down your affairs after your death (personal representative, executor, or successor trustee) must settle debts before distributing assets to your loved ones. The process of settling debts often requires creditor notification. Depending on state law, creditors have limited time to file claims against a deceased debtor’s estate. Publishing notice of the debtor’s death may shorten the amount of time that a creditor has to file their claim. However, name mismatches can alter this timeline. If debts are under a different name, creditors may not be properly notified, leading to disputed debts that extend probate and increase legal costs.
  • Searching for unclaimed property. States hold billions of dollars in unclaimed assets, such as bank accounts, uncashed checks, utility payment refunds, and insurance payouts. About one in seven people have unclaimed property held by their state’s treasuries, collectively amounting to billions of dollars in unclaimed property in the US.[7] When you pass away, your estate may need to search for unclaimed property to ensure that all your assets are accounted for. If your attorney does not know that you once went by the name Katherine E. Johnson or a nickname such as Kate Johnson, they might miss unclaimed property tied to those names, and your loved ones could lose out on assets that rightfully belong to them.

In addition to assets, creditors, and unaccounted-for and unclaimed property, name variations can disrupt the following:

  • Digital assets. Digital assets such as cryptocurrency wallets can be difficult for executors to access if they are not clearly documented or linked to your legal identity. Noncustodial wallets, in particular, may be unrecoverable without the seed phrase or private key, even if the executor knows they exist.
  • International assets. Assets abroad may use names adapted to local legal, linguistic, or cultural conventions. For instance, a property in Spain titled under the name Catalina Johnson might not match a US will’s reference to the same person, Katherine Johnson. Also, names may appear with spelling variations; in a different script (e.g., Cyrillic or Arabic); or reordered (i.e., last name appearing first).
  • Blended families. In blended families, name changes resulting from remarriage or adoption might confuse inheritance rights.
  • Taxes. Inconsistencies in names across financial accounts and tax documentation could potentially raise red flags with tax authorities during the estate administration process.
  • Beneficiary designations. Failure to update beneficiary designations on life insurance policies, retirement accounts, and payable-on-death or transfer-on-death accounts after a legal name change can lead to complications for your beneficiaries when they try to claim the benefits. Financial institutions could delay or deny payouts, and your loved one may need to provide proof of the name change to establish their identity.
  • Powers of attorney and healthcare directives. If your or your appointed agent’s name is legally changed after these documents are created, updating them is necessary to ensure that your agent’s authority is clearly recognized under their current legal name and that the documents are unequivocally tied to your current legal identity.

The last two examples show the importance of regularly reviewing estate planning documents to ensure that they reflect any name variations and new legal names for you, your estate plan’s beneficiaries, and your trusted decision-makers.

Make Name Changes a Part of Your Regular Estate Plan Updates

William Shakespeare famously wrote “a rose by any other name would smell as sweet” to mean that things are what they are, no matter what name we give them.

A name does not necessarily define who you are. However, name changes and variations can leave a sour taste in the mouths of beneficiaries, creditors, trustees, and executors when the time comes to settle your estate.

Many estate plans have not been touched since they were first created years ago and are woefully outdated. As part of the review process, you and your attorney should take the time to discuss any informal variations and formal legal changes to your name—and the names of your beneficiaries and decision-makers—to ensure a more accurate and effective estate plan. If you are just starting your plan, be sure to tell your attorney all your names. Call us to schedule an appointment to create or review your estate plan.


  1. Luona Lin, About 8 in 10 women in opposite-sex marriages say they took their husband’s last name, Pew Rsch. Ctr. (Sept. 7, 2023), https://www.pewresearch.org/short-reads/2023/09/07/about-eight-in-ten-women-in-opposite-sex-marriages-say-they-took-their-husbands-last-name. ↩︎
  2. Id. ↩︎
  3. Ethan Grant, The Rise of Hyphenated Last Names: Embracing Equality and Heritage in Modern Families, Bluenotary (Jan. 5, 2025), https://bluenotary.us/hyphenated-last-name. ↩︎
  4. Tovia Smith, When Hyphen Boy Meets Hyphen Girl, Names Pile Up, NPR (Jul. 19, 2012), https://www.npr.org/2012/07/19/156923573/when-hyphen-boy-meets-hyphen-girl-names-pile-up. ↩︎
  5. Steve Roy, What’s In A Name? Understanding Pseudonyms, Disqus (Dec. 15, 2014), https://blog.disqus.com/whats-in-a-name-understanding-pseudonyms. ↩︎
  6. Steinar Brandslet, Name change in the United States brought economic payoff, Norwegian SciTech News (Jun. 26, 2018), https://norwegianscitechnews.com/2018/06/name-change-united-states-economic-payoff. ↩︎
  7. What is unclaimed property? Nat’l Ass’n of Unclaimed Prop. Admins., https://unclaimed.org/what-is-unclaimed-property. ↩︎

The Deaths of Gene Hackman and His Wife

When investigators entered the home of legendary actor Gene Hackman and his wife, Betsy Machiko Arakawa, in a gated community outside Santa Fe, New Mexico, on February 26, 2025, they found the couple dead under mysterious circumstances.

Following their investigation, authorities pieced together a timeline of the couple’s last days, indicating that a period of about a week had passed between each of their deaths. The timing of their deaths matters not only for the criminal investigation but also for estate planning purposes, due to New Mexico’s simultaneous death rule. This rule can impact inheritance rights when spouses die close in time to each other and their estate plans do not address this scenario.

New Mexico’s Simultaneous Death Law

New Mexico’s simultaneous death law is a somewhat obscure estate law that could affect the distribution of Hackman’s and Arakawa’s estates.

Simultaneous death laws, such as the Uniform Simultaneous Death Act (USDA), enacted in 1940 and updated in 1993, were created to resolve legal uncertainties when two or more people die at the same time or close in time to each other and the order of death is unclear.

Before such laws, when two people—usually spouses—died at roughly the same time, the lack of clear evidence about who died first could lead to legal battles and inconsistent inheritance outcomes. Courts sometimes resorted to presumptions based on factors such as age or health that were arbitrary and unreliable, and assets could pass through one estate and then immediately to the next, resulting in unintended beneficiaries or excessive taxation.

The USDA created a more standardized approach and introduced a simpler standard: if two people die within 120 hours (5 days) of each other, they are treated as both dying before each other. That way, their assets pass to the next-in-line beneficiaries—not to each other—and avoid double probate.

Most states have adopted some version of the USDA. New Mexico’s version uses the 120-hour rule and presumes simultaneous death unless clear evidence proves otherwise.[1]

Variations exist across states, including slightly different timeframes, the standards of evidence needed to prove the order of death (and override the simultaneous death presumption), and how the law applies to specific property types. The law is only a default, meaning that it may not come into play if a will, trust, or other contractual agreement, such as an insurance policy, explicitly addresses simultaneous death with a survivorship clause that extends the time period beyond 120 hours.

How the Simultaneous Death Act Could Impact the Hackman and Arakawa Estates

Based on comments from the chief medical examiner and the latest details about their deaths, Hackman and Arakawa appear to have died about a week apart—Arakawa likely around February 11 and Hackman around February 18.[2] Assuming authorities accept this timeline, the New Mexico simultaneous death law will not apply because they were deemed to have died more than 120 hours apart. As a result, the distribution of their assets would be subject to their estate plans (if they created them) or estate intestacy laws (if they did not have estate plans). The following is an overview of how assets may be distributed in this case (1) with a valid estate plan extending the state’s default survivorship rule and (2) without an estate plan.

  • If Arakawa’s and Hackman’s wills included an extended survivorship provision: Reports indicate that Arakawa had a will leaving everything to Hackman. Also, it is said that her will included a survivorship clause requiring Hackman to outlive her by 90 days to inherit—overriding the standard 120-hour rule under state law. Since Hackman passed away about a week after her, he would legally be considered to have predeceased her under this 90-day survivorship rule. As a result, Arakawa’s contingent beneficiaries—reportedly various charities, as she had no children—would inherit instead of Hackman.
  • If they did not proactively plan to extend the survivorship period: Although it is not what happened in this case, it is worth considering how things could have played out if Arakawa and Hackman had not proactively prepared an estate plan and included extended survivorship provisions in their wills. Because Hackman survived Arakawa by more than 120 hours, he would have been considered the survivor under default state law and would have inherited Arakawa’s assets. Those assets would then become part of Hackman’s estate and be distributed according to his own will or, if none existed, under intestacy laws. In that scenario, both Arakawa’s assets and Hackman’s assets would likely pass to Hackman’s beneficiaries—presumably his three children—rather than the charities Arakawa intended to benefit if Hackman predeceased her.

Estate Planning Lessons: Timing and Details Matter

Celebrity deaths serve as a reminder of estate planning principles that may apply to ordinary individuals and situations. The circumstances of the Hackman-Arakawa deaths were unusual, but simultaneous deaths are fairly common. Simultaneous death laws apply beyond rare cases to scenarios such as car accidents, house fires, and natural disasters, and they emphasize estate planning’s universal importance.

Life is unpredictable. Estate plans must account for numerous contingencies, including the possibility of simultaneous or near-simultaneous deaths, especially among spouses or close family members. Default laws like simultaneous death statutes are meant to provide a framework when no specific planning exists. They cannot account for individual intentions or family dynamics.

Survivorship clauses are a dramatic example of how seemingly simple provisions can profoundly impact who ultimately benefits from your estate. By understanding the potential impact of simultaneous death laws and proactively incorporating tools such as survivorship clauses and contingent beneficiaries into your will or trust, you can take control of your legacy, protect your intended beneficiaries, and avoid the unintended consequences that may arise when these crucial considerations are overlooked.

Do not let fate—or the state—decide your estate plan. Make sure you have a will or trust that ensures your assets go where you want, specifies conditions and distribution timing, accounts for state laws, and is updated regularly to account for changing circumstances.

Be prepared for whatever the future holds: contact an attorney and take control of your estate plan.


  1. N.M. Stat. Ann. § 45-2-702 (2024), https://law.justia.com/codes/new-mexico/chapter-45/article-2/part-7/section-45-2-702/. ↩︎
  2. Edward Segarra, Gene Hackman’s autopsy reveals no hantavirus infection, which killed wife Betsy, USA Today (Apr. 28, 2025), https://www.usatoday.com/story/entertainment/celebrities/2025/04/28/gene-hackman-autopsy-hantavirus/83316365007. ↩︎
Your Divorce Decree: The First Step in Estate Planning

Your Divorce Decree: The First Step in Estate Planning

You and your spouse have recently divorced, and the judge has signed the divorce decree. Now what? Although you may feel that you have spent enough time and money on lawyers, there is one last attorney you need to talk to: an estate planning attorney. If you and your former spouse created an estate plan or named each other as beneficiary on any of your accounts or property (assets) while you were married, your divorce decree or state law may automatically revoke parts of that plan—particularly provisions naming your former spouse for decision-making roles such as executor, trustee, and agent under powers of attorney. However, not all changes happen automatically, and your former spouse could still remain a beneficiary of your trust, a joint property owner, or a named beneficiary on your assets. Additionally, appointments involving your former spouse’s family members are usually not revoked by law and may still be in effect. That is why it is necessary for you to review your estate plan with an attorney to ensure that your hard-earned money and property is distributed in a way that aligns with your new goals and life circumstances. If you have not done any planning since your divorce, now is the perfect time to get your affairs in order.

When you meet with the estate planning attorney, it is crucial that you bring all necessary documents, including a copy of your divorce decree. This document will help determine what obligations need to be included in your estate plan, what assets you now own, and how those assets are titled.

What Is in a Divorce Decree?

Support Obligations

Your divorce decree may state that your spousal or child support obligations require you to purchase life insurance to address the possibility that you pass away before fulfilling the entire obligation. If you have a child support obligation, it may be wise to designate your living trust as the beneficiary of the life insurance policy, if the terms of the divorce decree so permit. This approach would allow distributions to the minor children to be made by a trustee instead of as a lump-sum payout to your former spouse, who may not use the funds as intended.

Property Division

The divorce decree will also contain a section on the division of your marital property. It is helpful to provide this information to the estate planning attorney to present an accurate picture of your current property and financial accounts.

In addition to identifying the assets you now own, how you own them is incredibly important. Ownership of assets previously owned by you and your former spouse as joint tenants or tenants by the entirety may have changed to ownership as tenants in common under state law. This change is important to understand because, if you had passed away before your divorce, your now-former spouse would have automatically received your interest in the asset. However, if the ownership has changed to tenants in common, your interest will likely go to someone else when you pass away. If you do no planning, your interest in the asset will be transferred according to state law, which may not coincide with your wishes. It may go to your children, parents, or siblings, depending on who survives you. As part of your estate plan, you can choose who will receive your interest and how they will receive it.

What Effect Does the Divorce Decree Have on an Existing Estate Plan?

Last Will and Testament

Depending on the state in which you live, divorce can have a varying impact on your will. In some states, divorce revokes all provisions in your will that benefit your former spouse. Some state laws also revoke your former spouse’s appointment as personal representative. If you die before executing a new will, the law determines who receives your probate assets (generally your children if you have any; otherwise, your closely related family members in a predetermined order of priority). Even if gifts to your former spouse are automatically revoked by law after the divorce, gifts to your former spouse’s relatives—such as in-laws or your stepchildren—are not necessarily revoked. That is why it is essential to promptly update your estate plan to reflect any changes you wish to make.

Revocable Living Trust

As with wills, laws regarding what happens to a provision in a revocable living trust vary by state. Some state laws revoke all provisions relating to the former spouse, while others leave the trust intact. Although there may be provisions in the divorce decree that revoke all or part of your trust, it is important to review the trust documents and make any desired changes to avoid confusion. Also, in most states, gifts to your former spouse’s family under the trust may not be revoked as a result of the divorce.

Financial Power of Attorney

In some states, filing for divorce revokes the former spouse’s appointment as agent (the person who would act on your behalf) under a financial power of attorney. In other states, however, a divorce does not revoke your spouse’s ability to act as your agent. In either case, if there are any outstanding powers of attorney on file with third parties (e.g., at your bank or with a financial advisor), inform them of your divorce and provide them with a revocation or an updated power of attorney so they know that your former spouse is no longer authorized to act on your behalf.

Medical Power of Attorney

As with other estate planning documents, state laws vary as to whether your former spouse will still be able to make medical decisions for you if you are unable to make or communicate them yourself. Some states revoke the designation of your former spouse as your agent for medical matters as a result of the divorce, while others do not. In either case, it is incredibly important to keep this document up to date and to provide the updated versions to the necessary healthcare professionals.

Life Insurance

Because a life insurance policy is a contract with a third party, a divorce may have no effect on the beneficiary designations. If you named your former spouse as a beneficiary of the policy prior to your divorce, most states will not automatically revoke that designation after a divorce. Even if the designation is revoked under state law, it is important that you change the beneficiary designation so the company is on notice of your wishes and to avoid any confusion. In some cases, although the former spouse is no longer entitled to the life insurance proceeds, if the insurance company is not informed of the divorce or given an updated beneficiary designation, the benefit will be paid out to the named beneficiary (former spouse), and it will be the rightful beneficiary’s responsibility to sue and collect the proceeds from the former spouse. No matter what the applicable state law says, it is important to review and update your beneficiary designations after a divorce to avoid unnecessary drama and confusion.

Retirement Accounts

For retirement accounts governed by the Employee Retirement Income Security Act of 1974 (ERISA), such as 401(k)s, beneficiary designations are not automatically revoked upon divorce. Even if state law would otherwise remove a former spouse, ERISA preempts state law. To ensure that your former spouse does not receive the benefits, you must affirmatively change the beneficiary designation unless your divorce decree requires you to keep them as the beneficiary.

You Need an Estate Plan Now More Than Ever

As a newly single person, you are now in full control of your money and property. If you do not have an estate plan in place, state law will determine what happens to your hard-earned money and property. If you already have estate planning documents in place, you need to review them now that your circumstances have changed. Even if gifts to your former spouse are revoked under state law, you need to ensure that the alternate plan built into your documents is still what you want. Call us today so we can schedule an appointment to protect your new future and those you love, and do not forget to bring the divorce decree.

Estate Planning Strategies to Protect Your Spouse

Estate Planning Strategies to Protect Your Spouse

You found the love of your life, and as you have built your life together, you have likely weathered your fair share of storms and grown stronger because of them. Now that you are married, you are uniquely situated to provide meaningful support for your spouse after your passing through special estate planning tools available only to legally married individuals.

Lifetime Qualified Terminable Interest Property Trust

If one spouse individually owns more money or property than the other, a lifetime qualified terminable interest property (QTIP) trust allows the wealthier spouse (grantor spouse) to transfer money and property into the trust for the benefit of the less wealthy spouse (beneficiary spouse). This alternative is generally better than making outright gifts to a spouse because it may provide some creditor protection. A lifetime QTIP trust can also be a valuable strategy for couples in a second or subsequent marriage. During their lifetime, the beneficiary spouse will receive the income generated by trust assets and may also access trust principal for specific purposes such as healthcare, education, or other needs as defined by the grantor spouse. This structure allows the grantor spouse to provide for their partner during life while ultimately preserving the remaining assets for the grantor spouse’s children from a prior marriage or other chosen beneficiaries.

When the beneficiary spouse dies, the remaining property in the trust is included in their estate, making use of their unused federal estate tax exemption. If the beneficiary spouse dies first, the remaining trust property can continue (subject to applicable state law) for the grantor spouse’s benefit. If the lifetime QTIP trust is properly structured, any remaining trust assets may be excluded from the grantor spouse’s estate upon their death. After both spouses have passed, the remaining trust property is distributed to the beneficiaries designated by the grantor spouse when the trust was originally created.

A lifetime QTIP trust can offer meaningful benefits, but it may have unintended effects if a marriage ends in divorce. Because the trust is irrevocable, the former spouse could remain entitled to income for life unless the trust specifically defines the beneficiary spouse as the current spouse. With thoughtful drafting and the help of an experienced estate planning attorney, you can ensure that the trust reflects your wishes even if life takes an unexpected turn.

Spousal Lifetime Access Trust

A spousal lifetime access trust (SLAT) allows the grantor spouse to gift money or property into a trust for the benefit of the beneficiary spouse, protecting the money and property from creditors and estate tax while still allowing the grantor spouse to enjoy the money or property through the beneficiary spouse. Unlike a lifetime QTIP trust, this type of trust does not require that the beneficiary spouse be given access to the trust’s income. Instead, the beneficiary spouse may be given access to income or principal during their lifetime depending on the grantor spouse’s wishes. The goal of this strategy is to use the grantor spouse’s own estate tax exemption instead of the beneficiary spouse’s. Additionally, other beneficiaries, such as children or grandchildren, can be named as current beneficiaries of the trust.

Similar to lifetime QTIP trusts, SLATs also carry divorce-related risks. If you divorce, the beneficiary spouse retains access to property in the SLAT. However, the grantor spouse likely loses access to the trust upon divorce, as their only connection to the assets was indirectly through the beneficiary spouse. Since the SLAT is irrevocable, there is no way to undo the transfer or reclaim the assets. That is why many people include provisions limiting benefits to a current spouse or add other beneficiaries, such as children, to preserve flexibility.

Note: If both spouses want to use their own exemption during their lifetimes through estate planning tools such as SLATs, special attention needs to be paid to ensure that reciprocal trusts are not drafted, which could unwind all of the planning. As experienced attorneys, we can help ensure that both spouses’ goals are met in the most tax-efficient manner.

Community Property Considerations

If you and your spouse reside in or acquire property in a community property state, it is essential to determine the ownership interests in all property included in your estate plan. If community property is going to fund one of these trusts, it may be necessary to enter into a partition agreement or other marital agreement. Because this step may change the current ownership of the property, it is critical that you work with an experienced attorney who will explain the process and results.

Portability

With the exceptionally high estate tax exemption of $13.99 million per person in 2025, you may feel that you do not need to worry about estate tax reduction strategies. However, this provision will sunset on December 31, 2025, unless Congress takes additional action. If you die in 2026 or after, there is a possibility that the estate tax exemption could be reduced back to $5 million, adjusted for inflation. Unfortunately, without a crystal ball, there is no way to know what the exemption amount will be if you die after the sunset date. However, portability is a handy tool for battling this uncertainty.

Portability allows a surviving spouse to use any unused portion of their deceased spouse’s federal estate and gift tax exclusion—known as the deceased spouse’s unused exclusion (DSUE) amount. This means that the surviving spouse can combine their own exclusion with what remains of their spouse’s, which increases the amount that the surviving spouse can transfer free of gift and estate tax. However, to take advantage of portability, a federal estate tax return (Form 706) must be timely filed (usually within nine months of the deceased spouse’s death, or longer if an extension has been granted) when the first spouse passes. Without this filing, the surviving spouse will lose the DSUE amount and will have only their own exclusion amount to use.

Note: The DSUE can be used only for your most recently deceased spouse. If you remarry, you must use the first spouse’s DSUE before your new spouse dies—otherwise, you will lose the ability to use the first spouse’s unused exclusion.

We Are Here to Help

You work every day to build a wonderful life for yourself and your family. We are here to help design a unique plan to ensure that you, your spouse, and your family will be taken care of now and upon your passing. Call us today to schedule an appointment to discuss how we can help.

Leafy tree split at the trunk with roots exposed

Want to Disinherit Someone? This Is What You Need to Know

Disinheritance—the intentional exclusion of a family member, usually a child or spouse, from receiving part of your estate after your death—is more common than you might think. It is also easier than you might think to disinherit a loved one, with a couple of notable exceptions. However, it is not as simple as omitting someone’s name from your estate plan.

Depending on their relationship to you and the laws in your state, some people may have legal rights to a portion of your assets (e.g., money, investment accounts, and property) when you die, unless you take specific steps to prevent them from inheriting. Even then, the decision to disinherit someone can lead to disgruntled family members and legal challenges, so the situation must be approached with care, both legally and emotionally.

Disinheritance Laws: Who You Can (and Cannot) Disinherit

You are generally—but not entirely—free to dispose of your assets at your death however you see fit. This ability to include, as well as exclude, people from your estate plan is known as testamentary freedom.

Before delving into how to disinherit someone, let’s look at who might be disinherited and the legal protections they may have against disinheritance.

Spouses

Disinheriting a spouse is often the most legally complex scenario. Spouses have significant inheritance protections, regardless of what your estate plan says. For example:

  • Elective share laws. In most states, a surviving spouse has the right to claim an elective share of the assets owned solely by you, thereby protecting them from total disinheritance. The amount that can be elected varies by state but may be around one-third to one-half of your separately owned property. Some states offer a larger share to surviving spouses as the length of the marriage increases. 
  • Community property states. If you live in a community property state (such as California, Texas, or Arizona), assets acquired during marriage are typically considered jointly owned, and your spouse automatically has a right to half of the community property. Disinheriting a spouse in these states may apply only to your separate property.

These laws make completely disinheriting a spouse challenging—though not entirely out of reach. With careful planning, strategies like prenuptial or postnuptial agreements can be used to waive a spouse’s inheritance rights, even in states with elective share or community property regimes. While these approaches require thoughtful drafting and mutual consent, they offer a path for clients whose estate planning goals call for greater control over the ultimate distribution of their assets.

Children

When it comes to disinheriting your children, you have fairly broad testamentary freedom.  However, children are afforded some protections under applicable state law that may prevent complete disinheritance.

Many states have statutory allowances—such as the family allowance, exempt property allowance, and homestead allowance—that serve as built-in protections for minor or dependent children (the term dependent children may even include adult children in some states and in some circumstances). These allowances ensure that, even if a child is not named in a will or trust, they are guaranteed a minimum level of support from the estate.

In addition, if a parent passes away while still owing child support—whether from a court order or a divorce settlement—that obligation typically does not vanish with their death. In most cases, the unpaid support becomes a debt of the estate and must be addressed before assets are distributed to heirs or beneficiaries. This ensures that the child’s financial needs continue to be prioritized, even after the parent’s passing.

Siblings, Parents, and Others

Siblings, parents, and more distant relatives (such as cousins or nieces and nephews) have no automatic right to inherit unless you die without a will (intestate) and these people are next in line under your state’s inheritance laws. In most cases, this only happens if you have no surviving spouse or children.

Disinheriting these individuals is relatively straightforward, since they are unlikely to have legal grounds to challenge your estate plan. Still, to deliberately keep a parent, sibling, aunt, uncle, or other extended relative from inheriting your assets, you need to explicitly and unambiguously write this into your will or trust and designate the specific individuals or charities that you do want to inherit from you.

Others Who Might Expect Something

Sometimes, the person you want to disinherit is not a family member but a close friend, business partner, or caregiver who might expect to receive something. If you have promised them an inheritance in the past (verbally or otherwise) or suggested it in passing, they might try to contest your estate plan if they are not included. Their claims are unlikely to succeed in court, but explicitly excluding them in your estate plan documents can clarify your intentions and eliminate ambiguity and potential lawsuits.

What Happens If You Do Not Have an Estate Plan?

Dying without a will or trust means that your state’s laws determine who inherits your assets. These laws, known as intestacy rules, prioritize close family members in a specific order, typically the following:

  1. Spouse
  2. Children
  3. Grandchildren
  4. Parents
  5. Siblings
  6. More distant relatives

Surveys consistently show that only around one-quarter of Americans have an estate plan.[1] If you want to disinherit someone who would inherit under intestacy laws, you must have an estate plan. Absent a formal, written plan that states your intentions, the wrong person could receive a portion of your assets by default.

For example, say you are estranged from a sibling and die without a will. That sibling might inherit part of your money and property if you have no surviving spouse, children, grandchildren, or parents, even though you do not want them to inherit anything.

How to Disinherit Someone

Disinheriting someone requires a clear and unambiguous statement in your estate planning documents. Leaving their name out of your plan is not enough. The court could assume that an omitted name is unintentional and award them a share of your money and property, especially if the person is a close family member. To disinherit someone, you should take the following steps:

  • Make your intent explicit. Your estate plan should explicitly state that you do not want a certain individual to receive any portion of your money and property. Use straightforward language. For example:
    • “I am deliberately excluding [name] from receiving any portion of my estate.”
    • “I specifically direct that my son, [name], shall receive none of my property, whether real or personal.”
  • Identify the individual clearly. Use the full legal name of the person you wish to disinherit to avoid any confusion with individuals who may have similar names. For further clarity, you can include their relationship to you, their date of birth, and other distinguishing information, such as their city and state of residence. For example:
    • “I am intentionally omitting my son, Matthew James Walker, born March 2, 1988, currently residing in Seattle, Washington, from any share of my estate. He shall take nothing under this Will.”
  • Keep it brief and neutral. Your estate plan is not the place to air grievances or explain your decision in detail. Most people do not realize that wills are public documents and the things they write in them live on in public view and might cause reputational harm. Even if you are trying to explain a disinheritance, making potentially false, damaging claims can expose your estate to legal risk.
    • Writing something such as “I leave nothing to my daughter, Anna Smith, because she is a drug addict and a thief and has embezzled money from her employer” could expose your estate to a claim of testamentary libel—a defamatory statement made in a will that could damage someone’s reputation.
    • Emotionally charged language could also inadvertently create grounds for a legal challenge based on duress or undue influence claims.
    • Keep your language brief and neutral (e.g., “I make no provision for my daughter, Anna Smith, due to personal reasons known to both of us.”).
  • Explain your thinking in an (optional) letter. If you feel compelled to explain your decision and have not already discussed it with the person you are disinheriting, consider writing a separate letter to them. Store the letter privately and instruct that it be shared only after your passing. This is not a legally binding document and should not be attached to your will or trust. By explaining your reasons for the disinheritance, you may help reduce the chances of a family member challenging your will or trust later on—especially claims that you lacked capacity or were influenced by someone else. A clear statement of intent can go a long way toward preventing misunderstandings and minimizing the risk of litigation.

Alternatives to Disinheritance

There is anecdotal evidence that more parents are not leaving their children inheritances to avoid entitlement and promote self-reliance. Some celebrities have publicly vowed to leave their kids little or nothing, and this trend may be trickling down to ordinary Americans.

One recent survey found that just 26 percent of Americans plan or expect to leave behind an inheritance.[2] Parents may want to spend the money on themselves in retirement, or they may be forced to spend it on healthcare and long-term care. They may also decide that their money is better spent on charitable giving, that it should go to someone who needs it more, or that they will embrace “gifting while living” and pass their hard-earned assets to their children now.

However, leaving an inheritance does not have to be all or nothing. If you are unsure about fully disinheriting someone or want to avoid potential conflict or legal challenges, consider these alternatives:

  • Leave a smaller or symbolic inheritance. Instead of cutting someone out entirely, leave them a small token gift, such as a few hundred dollars or a family heirloom, to signal that you thought of them and did not accidentally omit them.
  • Use a no-contest clause. A no-contest clause provides that anyone who challenges your will or trust loses their inheritance. You can combine this type of clause with a modest gift to discourage lawsuits since the beneficiary stands to lose something if they challenge your will or trust. Keep in mind that no-content clauses may not be recognized or enforceable under your state law.
  • Create a trust. A spendthrift trust can help protect a financially irresponsible beneficiary from reckless spending and shield the inheritance from creditors. Similarly, a conditional or incentive trust allows you to set goals or milestones that must be met before funds are distributed. These tools offer a thoughtful way to provide for someone you may be hesitant to give money to outright, while still protecting their long-term well-being and interests.
  • Add beneficiaries to accounts. Retirement accounts, life insurance policies, and some types of bank accounts and deeds pass directly to your named beneficiaries (i.e., those other than the disinherited loved one) and bypass the need for a will and public probate process entirely. These distributed assets will only be known to the named beneficiary and the government for tax purposes, which could help keep the distribution private and prevent a will contest.

In addition to seeking a compromise to disinheritance where appropriate, make sure to review and update your estate plan regularly in case you have had a change of heart or circumstances.

Work with an Attorney to Avoid the Personal and Legal Challenges of Disinheritance

Disinheritance can be emotionally fraught and legally tricky. It is a deeply personal decision that should be approached with careful consideration and sound professional advice.

The law respects your right to choose how your assets are distributed. It also requires that those choices are expressed clearly and meet legal requirements. An estate planning attorney can help you draft documents that comply with state laws and anticipate challenges, include provisions to strengthen your plan, and explore options such as trusts that are harder to challenge and more private than wills. For a plan that reflects your convictions and stands up in court, schedule a meeting with us.


  1. Victoria Lurie, 2025 Wills and Estate Planning Study, Caring (Mar. 31, 2025), https://www.caring.com/caregivers/estate-planning/wills-survey. ↩︎
  2. As $90 Trillion “Great Wealth Transfer” Approaches, Just 1 in 4 Americans Expect to Leave an Inheritance, Nw. Mutual (Aug. 6, 2024), https://news.northwesternmutual.com/2024-08-06-As-90-Trillion-Great-Wealth-Transfer-Approaches,-Just-1-in-4-Americans-Expect-to-Leave-an-Inheritance. ↩︎
Three Estate Planning Mistakes Farmers and Ranchers Make—and How to Avoid Them

Three Estate Planning Mistakes Farmers and Ranchers Make—and How to Avoid Them

Farming and ranching is more than just a livelihood; it is about preserving a legacy and a way of life. Unfortunately, many farmers and ranchers fail to create a comprehensive estate plan—or any estate plan at all. Without a proper estate plan, the family farm or ranch, passed down for generations, can end up being sold and converted to nonagricultural use, cutting the family’s legacy short and ending their unique lifestyle.

Below are three common estate planning mistakes farmers and ranchers make and how to avoid them.

Mistake #1—Failing to Plan

As a farmer or rancher, you have distinct estate planning needs. You may have children who want—or do not want—to continue the farming or ranching business. You have to consider who should inherit your land, equipment, livestock, accounts, and other property, while trying to keep things fair and equal. As a result, you may be unable to decide what to do and end up doing nothing at all.

Fortunately, many estate planning options are available that will help you fulfill your ultimate goals for the future. To preserve what you have and leave it to the next generation, you need to work with a team of experts, including attorneys, accountants, bankers, insurance specialists, and financial advisors, who are familiar with the nuances of estate planning and its intersection with farming or ranching legacies to ensure that the plan will work as anticipated when it is needed.

Mistake #2—Relying on Joint Ownership

You may believe that the easiest way to avoid having your loved ones go through the probate process at your death is to own your property jointly with them. However, transferring all or part of your farm during your lifetime may have unintended consequences. For example, farmland or ranch property that is jointly owned and enrolled in programs administered by the United States Department of Agriculture may result in subsidies being left on the table. In addition, joint ownership causes you to give up total and unilateral control of your real estate. Someone added as a joint owner to your account or property can make decisions about it: They may withdraw money from the account without your knowledge or consent. They can also prevent the property’s sale if they disagree with your decision to sell. Your co-owner’s creditors may also be able to go after jointly owned accounts and property. Unlike other planning options, joint ownership may not be easy to change, since “undoing” joint ownership can have significant costs and tax implications.

Holding real estate in the name of a business entity (corporation, partnership, or limited liability company) or a trust is a better option, as it allows you to minimize liability and retain control.

Mistake #3—Overlooking Liquidity Needs

Incapacity (the inability to manage your own affairs) and death are expensive life events and often require cash to pay expenses. However, farmland and farming equipment are not easily converted to cash. Without properly planning for immediate and long-term cash needs, your family may be forced to quickly sell land and equipment for pennies on the dollar.

You have several options when creating a plan to manage debt and expenses during your incapacity or after your death. Financial advisors, bankers, and insurance professionals can assist with securing lines of credit and the proper amount of disability, long-term care, and life insurance to prepare for the unexpected. Attorneys can assist by creating life insurance trusts, business entities, and other, more complex plans.

Final Thoughts on Estate Planning for Farmers and Ranchers

We understand that farmers and ranchers require specialized estate planning solutions. A team of advisors, including attorneys, accountants, bankers, insurance professionals, and financial advisors, can assist you in creating and maintaining a plan that will preserve your legacy and unique way of life. Our firm is experienced in supporting farmers and ranchers with achieving their estate planning goals. Please call our office if you have any questions about this type of planning and to arrange for a consultation.

How an Inheritance Can Enhance Your Loved One’s Educational Experience

How an Inheritance Can Enhance Your Loved One’s Educational Experience

A primary goal of estate planning is to financially provide for your loved ones. One way to ensure that they are set up for lifelong success is with an inheritance that pays for their education.

Higher levels of education are positively correlated with better life outcomes, including improved health, longer lifespans, and higher incomes.[1] However, education costs across all levels have risen significantly, pushing a good education out of reach for many families and saddling students with debt that can take decades to pay off.[2]

From primary school to postgraduate studies, you can invest in a loved one’s education and maximize their potential through your estate plan. Options include direct payments, 529 plans, and money from a will or trust, often with associated tax breaks.

While educational gift options abound, their legal mechanics, tax implications, and benefits differ depending on when and how they are given, and restrictions may apply.

Higher Education = Greater Well-Being—but at What Cost?

The economic and noneconomic benefits associated with a college degree are well established.

Compared with people who completed only a high school diploma, those with undergraduate degrees not only earn significantly more on average over their lifetimes and are less likely to be unemployed but also tend to enjoy better health and a higher quality of life, including higher job satisfaction, improved self-esteem, improved access to healthcare, and increased civic engagement.[3]

According to the United States Bureau of Labor Statistics, people with a bachelor’s degree earn two-thirds more than high school graduates.[4] Over the course of their working years, college graduates typically earn around $1 million more than their degreeless peers.[5]

Although the economic advantages of a college degree vary based on the degree earned[6]—and despite the rising costs of postsecondary education—most Americans recognize the value of college and view a degree as a “golden ticket” to prosperity.[7]

However, earning a college degree has never been more expensive, and these costs are forcing some Americans to rethink whether it is worth the investment.

Tuition and fees have tripled since the 1960s, jumping by 60 percent between 2000 and 2022, from around $9,000 to nearly $15,000 per year.[8] From 2010 to 2022, average annual tuition and fees went from $12,979 to $14,688—a 13 percent increase.[9]

These rising costs, which include room and board, books, and other supplies in addition to tuition, are discouraging many students from attending college and contributing to enrollment declines.[10]

The average federal student loan debt balance in 2024 was nearly $40,000, while the total average balance (including private loan debt) is even larger.[11] Today, the typical public university student borrows almost $32,000 to earn a bachelor’s degree.[12] Far from the “golden ticket” of a degree, student loan debt can limit wealth building and upward mobility instead of opening doors.

Costs are also rising at K–12 private schools, which are generally considered a gateway to higher education. Research shows that private schools are better than public schools at preparing students to enter college, most likely due to their higher scores on standardized tests and more-demanding graduation requirements.[13] However, the average annual private school tuition is $12,000–$13,000, including about $9,000 for private elementary school and roughly $16,000 for private high school.[14]

Today, a student who attends private schools from kindergarten through four years of postsecondary study can expect to pay more than $300,000.[15]

As college enrollment declines, trade programs are picking up the slack. Trade and vocational schools are usually a much cheaper option than a traditional four-year college. Programs cost approximately $5,000 to $20,000 and are often completed within two years.[16] Enrollment in these programs, which many young people see as a quicker and more affordable path to a good job, has seen strong growth, including double-digit increases in some fields.[17]

In addition, students who take advantage of internships and externships while in college have improved employment prospects.[18] However, even a paid internship can impose costs on students, such as housing, transportation, and other living expenses.

Family Contributions Are Vital to Achieving Educational Goals

Families are a significant funding source for education at all levels. For example, parents contributed an average of $13,000 per year toward undergraduate education costs.[19] Family financial help can also play a major role in paying for trade school, private K–12 school, and internship-related expenses.

Every dollar a family invests in a loved one’s education alleviates their potential debt burden and fast-tracks their future success. To make your legacy a launchpad for their achievements, consider the following educational gifts and their potential tax benefits:

  • Direct tuition payments. Tuition paid directly to an educational institution is not considered a taxable gift.[20] This exemption applies to K–12 schools, colleges, and trade schools but covers only tuition—not room and board, books, or other expenses. It allows parents, grandparents, or other relatives to contribute without using their annual or lifetime gift tax exclusion.
  • 529 plans. Contributions grow tax-free, and withdrawals for qualified educational expenses (tuition, fees, books, room and board, computers) are also tax-free at the federal level. Since 2018, funds from 529 plans can be used for K–12 tuition (up to $10,000 per year). Some states offer tax deductions or credits for contributions, and, starting in 2024, unused funds can be rolled into a Roth IRA for the beneficiary (subject to limits).
  • Coverdell education savings accounts (ESAs). Contributions (subject to limitations and capped at $2,000 per year per beneficiary) are not tax-deductible, but earnings grow tax-free if used for qualified educational expenses, from kindergarten to higher education, including tuition, fees, books, supplies, tutoring, and certain technology needs, and they provide flexible investing options.

While tax benefits make it appealing to use those savings for a loved one’s education, not all education-related expenses fit the rules laid out above. Some expenses happen outside the classroom and may impose additional student costs that families can help cover. For example:

  • Internships and externships. Even if the program pays the participant a small sum, the amount may not cover the expenses associated with participating in the program, such as rent (if the program is in a different city or state), food, insurance, etc.
  • School field trips. Depending on the trip, the cost to participate can be expensive. Setting aside money for your loved one to participate in such activities can allow them to have additional life experiences that will shape them even after you have passed away.

You can support your loved one’s future by setting aside funds in a trust specifically for these types of expenses.

Gift Timing

Education funding can take place during your lifetime or after you die. Lifetime gifts use gift tax rules. Postdeath gifts fall under estate tax rules that are applied at death.

However, because the lifetime gift and estate tax are unified, using one affects the other, and lifetime and postdeath estate planning strategies should not be viewed separately. You might, therefore, use a mix of lifetime and posthumous educational gift strategies. Consider these common scenarios:

During Life

  • Direct tuition payments. You can pay tuition to an educational institution at any time while you are alive, and it is immediately exempt from gift tax.
  • 529 plans. You can establish and fund a 529 plan while alive, taking advantage of tax-free growth over time and the ability to front-load five years’ worth of annual exclusions ($95,000 in 2025). You control the account and can adjust beneficiaries as needed.
  • Payments to loved ones for a specific purpose. Currently, you can give $19,000 per year per recipient tax-free during your life for any purpose, including nontuition expenses such as internship costs or field trips, reducing your taxable estate while you are alive.

After Death (via Will or Trust)

  • Direct tuition payments. You can set up a will or trust to allocate funds for tuition, directing your executor or trustee to pay educational institutions on behalf of a loved one.
  • 529 plans. You cannot fund a 529 posthumously through a will because it is a lifetime savings vehicle tied to a living account owner. However, you could name a successor owner (e.g., a spouse or child) for an existing 529, or your estate could distribute funds to a beneficiary who then opens a 529, though this option loses the predeath tax-free growth benefit. After your death, the executor of your estate or the successor trustee of your trust can distribute the funds to an existing 529 plan, depending on what your will or trust instructs and what funds are available. Note that the contributions from a will or trust will not qualify for the gift tax exclusion and will still be part of the taxable estate. It is also important to clearly name the account beneficiary and owner, since the account owner will control how the funds are used.

You might also consider using a trust created via your will (testamentary trust) or funded during your life (revocable living trust) that offers gifting flexibility. You can instruct the trustee to pay for tuition, tech, or living expenses, mimicking lifetime strategies. Trusts can also be tailored (e.g., “pay tuition directly to schools” or “distribute $10,000 yearly for education”).

Whether it incorporates a gifting-while-living strategy or a standard inheritance, your estate plan can unlock the power of education while leveraging tax breaks. Schedule a meeting with us today to discuss specific strategies and which one is best for you and the student in your life.


  1. Anna Zajacova & Elizabeth M. Lawrence, The relationship between education and health: reducing disparities through a contextual approach, Annual Rev. of Pub. Health vol. 39 (Jan. 12, 2018), https://pmc.ncbi.nlm.nih.gov/articles/PMC5880718. ↩︎
  2. Adam Looney, How Much Does College Cost, and How Does It Relate to Student Borrowing? Tuition Growth and Borrowing Over the Past 30 Years, Higher Educ. Today (Sept. 9, 2024), https://www.higheredtoday.org/2024/09/09/surprising-trends-in-college-costs-and-student-debt. ↩︎
  3. Shayna Joubert, 10 Benefits of Having a College Degree, Northeastern Univ. (Nov. 15, 2024), https://bachelors-completion.northeastern.edu/news/is-a-bachelors-degree-worth-it. ↩︎
  4. Employment Projections, U.S. Bureau of Labor Statistics (Aug. 29, 2024), https://www.bls.gov/emp/chart-unemployment-earnings-education.htm. ↩︎
  5. How does a college degree improve graduates’ employment and earnings potential?, Ass’n of Pub. and Land-Grant Univs., https://www.aplu.org/our-work/4-policy-and-advocacy/publicuvalues/employment-earnings (last visited Apr. 22, 2025). ↩︎
  6. Economic Benefits: How College Graduates Earn More Over a Lifetime, Baker Coll. (Nov. 27, 2024), https://www.baker.edu/about/get-to-know-us/blog/is-college-worth-it-benefits-of-going-to-college/#:~:text=For%20example%2C%20certain%20tech%2Doriented,not%20kept%20up%20with%20inflation. ↩︎
  7. Preston Cooper, Does College Pay Off? A Comprehensive Return on Investment Analysis, Freopp (May 8, 2024), https://freopp.org/whitepapers/does-college-pay-off-a-comprehensive-return-on-investment-analysis. ↩︎
  8. Jessica Bryant, Cost of College Over Time, Best Colls. (Feb. 25, 2025), https://www.bestcolleges.com/research/college-costs-over-time. ↩︎
  9. Id. ↩︎
  10. Id. ↩︎
  11. Melanie Hanson, Student Loan Debt Statistics, Educ. Data Initiative (Mar. 16, 2025), https://educationdata.org/student-loan-debt-statistics. ↩︎
  12. Id. ↩︎
  13. Marthy Naomi Alt & Katharin Peter, Private Schools: A Brief Portrait, p. 26, Nat’l Ctr. for Educ. Stat. (Aug. 2022), https://nces.ed.gov/pubs2002/2002013.pdf. ↩︎
  14. Melanie Hanson, Average Cost of Private School, Educ. Data Initiative (Aug. 29, 2024), https://educationdata.org/average-cost-of-private-school. ↩︎
  15. Id. ↩︎
  16. Lyss Welding, How Much Does Trade School Cost?, Best Colls., (May 23, 2024), https://www.bestcolleges.com/research/how-much-does-trade-school-cost. ↩︎
  17. Olivia Sanchez, Trade programs—unlike other areas of higher education—are in hot demand, The Hechinger Rep. (Apr. 17, 2023), https://hechingerreport.org/trade-programs-unlike-other-areas-of-higher-education-are-in-hot-demand. ↩︎
  18. Diane Galbraith, Ph.D. & Sunita Mondal, Ph.D., The Potential Power of Internships and The Impact on Career Preparation, 38 Rsch. in Higher Educ. J. 3, https://files.eric.ed.gov/fulltext/EJ1263677.pdf (last visited Apr. 22, 2025). ↩︎
  19. What Percentage of Parents Pay for College?, Going Merry (May 30, 2024), https://goingmerry.com/blog/what-percentage-of-parents-pay-for-college. ↩︎
  20. I.R.C. § 2503(e), https://www.govinfo.gov/content/pkg/CFR-2010-title26-vol14/pdf/CFR-2010-title26-vol14-sec25-2503-6.pdf. ↩︎
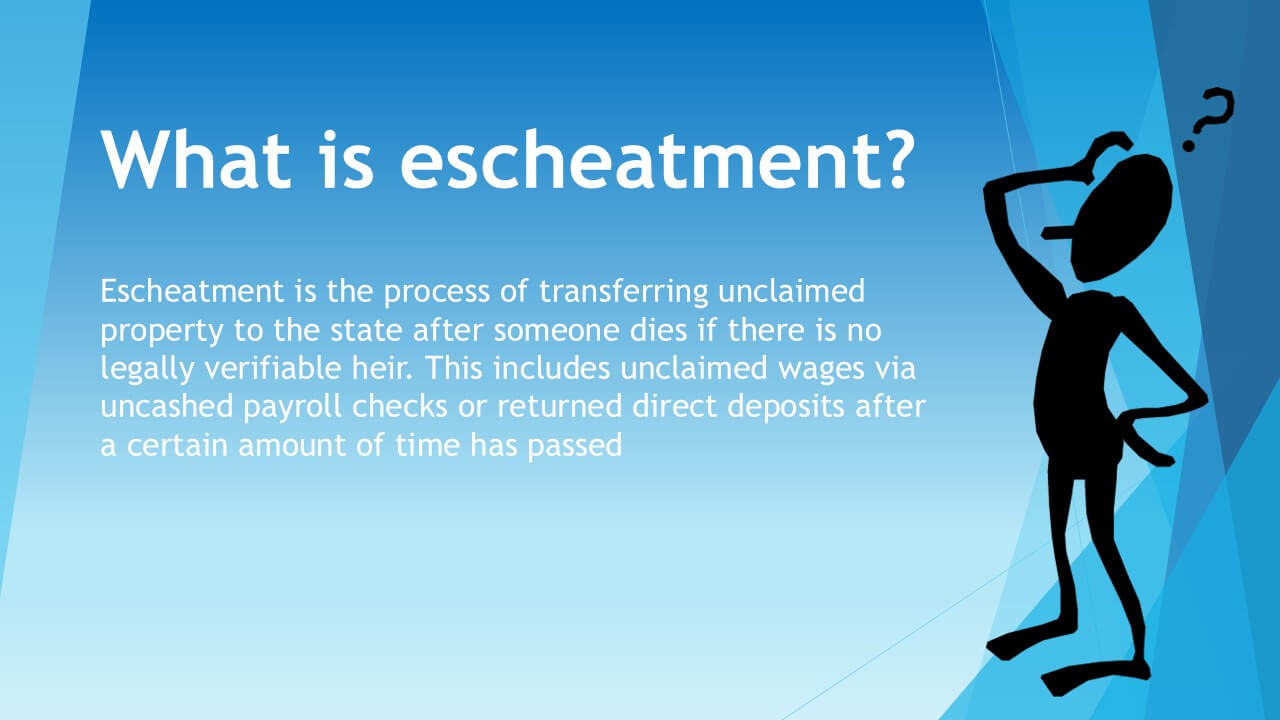
Explainer slide on escheatment and unclaimed property rules.

Do Not Let Your Money and Property Go to the State: Why You Need an Estate Plan

Americans tend to bristle when any level of the government meddles in their private lives, especially with their money. Look no further than the famous “death and taxes” quote for a sense of how Americans feel about bureaucratic creep and government’s sticky fingers.

You may take pains to minimize government meddling in your personal affairs during your lifetime, but if you do not have an estate plan, you may die intestate, and state law will become heavily involved in what happens to your money and property—and may even end up claiming it for itself through a process called escheat.

To avoid these outcomes, you need an up-to-date estate plan that lets you exercise maximum control and autonomy, both in life and in death.

Escheatment and the State’s Taking Power

Escheat is a term that dates to feudal times when, if a tenant died with no blood relatives, their estate reverted to the lord of the manor as the ultimate landowner. Middle English referred to this practice as eschete, which evolved into our modern state escheatment laws.

Today, every US state has laws requiring that unclaimed or abandoned property be turned over to the state after a designated period of inactivity—called the dormancy period—which typically ranges from one year to five years, depending on the state.

Unclaimed property can be tangible or intangible and includes assets such as 401(k)s, inherited individual retirement accounts (IRAs), taxable investments, bank savings, and other financial assets in accounts that have been inactive for a while and are legally deemed to be dormant.[1]

Unclaimed property also includes life insurance proceeds and assets such as gift certificates, uncashed checks, and personal property held in safe deposit boxes.[2]

States hold billions of dollars in unclaimed property taken by escheatment.[3] Unclaimed property is a major source of revenue for some states.[4] It is the fifth largest funding source for California, for example, and the third largest source for Delaware.[5]

As of 2025, California alone holds about $14 billion in unclaimed assets.[6] It and other states are taking more measures to enforce escheat laws to claim unclaimed property, often shortening dormancy periods and reducing notification requirements to capture more assets, according to NPR.[7] 

Escheat and Intestacy

A 2025 Caring.com survey found that just 24 percent of Americans have a will.[8] Put another way, three out of four Americans are likely to die intestate because of their lack of preparation.

Also, many Americans who have estate plans have not updated them in years, which puts assets at risk of being unidentified and unclaimed.[9]

Both scenarios can ultimately lead to the state claiming your money and property after your death through escheatment proceedings in probate court. If you pass away and do not have a legal document such as a will or a trust that clearly identifies who should receive your money and property, you are said to have died intestate. If you die intestate, state laws—called intestacy statutes—will determine who inherits from you.These laws generally start with next of kin, but if there are no family members to receive your money and property, your money and property could end up going to the state instead of supporting your nonfamily loved ones or a favorite charity.

This practice, a throwback to feudal times, essentially makes the state the default heir—the lord of the manor—and you a mere tenant.

Another possibility is partial intestacy, which occurs if you die with a valid will but the will does not fully address everything you own. Intestacy rules will apply to those remaining accounts and property. 

If You Want Something Different, Update Your Plan

It is not only dying intestate that can trigger state escheat and intestacy laws. You could have an out-of-date or incomplete plan that fails to include a comprehensive inventory of everything you own. Because loved ones might not have a full picture of what you own or where to find it, those accounts and property could be unclaimed for several years and ultimately end up in state custody.In other words, a good estate plan leaves a trail of breadcrumbs for your executor or trustee to follow so they can identify, gather, and distribute everything you own, leaving nothing behind for the state.

A comprehensive estate plan also lets you take control and decide exactly who inherits what. Estate planning allows for nuances that state laws do not and can make all the difference between crafting an intentional legacy and being subject to the state’s default legacy for you.

Some scenarios that an estate plan can address—and state law cannot—include the following:

  • Stepchildren. Under most intestacy laws, stepchildren do not automatically inherit anything unless you have legally adopted them. If you raised a stepchild as your own and want them to inherit, you will need a will or trust to make that happen in most states.
  • Unmarried partner. In most states, unmarried partners have no legal right to each other’s money and property under intestacy laws, regardless of how long they have been together. This can result in a situation where a long-term partner is left with nothing, while estranged relatives or the state claim the money and property left behind.
  • Close friend. Intestacy laws do not recognize friendships. To leave something to these very important people in your life, you must spell it out in your estate plan.
  • Charity. You may prefer that your money go to a cause you are passionate about, such as animal welfare, education, or medical research. Charities will not see a dime unless you explicitly designate them as beneficiaries.
  • Specific bequests. Want to leave your antique watch to your nephew or your art collection to your niece? Intestacy laws distribute money and property generally and do not carve out gifts of specific items.
  • Control over guardianship. A will allows you to nominate a guardian to care for your minor children. Lacking this crucial designation, the court will decide without input from you, and the person they select may not be your preferred choice.

Take Control with an Estate Plan

Legal jargon such as escheat and intestate may put people off from the estate planning process entirely. Even the term estate can suggest an exclusive service only for the wealthy.

In reality, estate planning is for anyone who owns anything of value—monetary, sentimental, or otherwise—and who cares about what happens to it. Delaying estate planning can cause conflicts in your family.

If you want to exercise maximum control over your hard-earned money and property and ensure that the state does not end up claiming it, you should have at least a basic will. However, you can exercise even greater control and likely avoid probate court altogether with a trust-based estate plan. Do not settle for the state’s default rules and leave things to chance—or the government. Take charge of your legacy today: call us so we can craft a plan unique to you or update your existing plan.


  1. What Is Unclaimed Property, Nat’l Ass’n of Unclaimed Prop. Adm’rs, https://unclaimed.org/what-is-unclaimed-property (last visited Apr. 17, 2025). ↩︎
  2. Id. ↩︎
  3. Report Shows Unclaimed Property Administrators Returned over $2.8B to Americans During FY 2020, Nat’l Ass’n of Unclaimed Prop. Adm’rs, https://unclaimed.org/fy20-annual-report (last visited Apr. 17, 2025). ↩︎
  4. Unclaimed Property FAQ, Unclaimed Prop. Pros. Org., https://www.uppo.org/page/UnclaimedPropFAQ (last visited Apr. 17, 2025). ↩︎
  5. Escheat Show, NPR (Jan. 24, 2020), https://www.npr.org/transcripts/799345159. ↩︎
  6. Kendrick Marshall, California Is Holding $14 Billion in Unclaimed Property. Here’s How to Get Your Share, Sacramento Bee (Mar. 28, 2025), https://www.sacbee.com/news/california/article301817649.html. ↩︎
  7. Audrey Quinn, When Your Abandoned Estate Is Possessed by A State, That’s Escheat, NPR (Feb. 13, 2020), https://www.npr.org/2020/02/13/805760508/when-your-abandoned-estate-is-possessed-by-a-state-thats-escheat. ↩︎
  8. Victoria Lurie, 2025 Wills and Estate Planning Study, Caring (Feb. 18, 2025), https://www.caring.com/caregivers/estate-planning/wills-survey. ↩︎
  9. Id. ↩︎

Small gray home with brick chimney and colorful spring flowers.

Should I Buy a Home with Someone Other than a Spouse?

Rising housing costs, the desire for companionship, and the need to share resources are increasingly leading buyers to consider co-owning a home with someone other than a spouse, such as a friend, relative, or significant other.

Although this arrangement can be beneficial on several levels, it should be approached with open communication, careful planning, and a clear understanding of the financial and legal implications.

Co-Ownership on the Rise

Whether the reason for home co-ownership is affordability, companionship, shared responsibilities, investment opportunity, or some mix of these, the numbers tell the story of how nonspouse co-ownership is increasing.

Data from Zillow shows that 62 percent of buyers share ownership of their home with at least one other person, but just 50 percent co-bought with a partner or spouse.[1] Fourteen percent co-bought a home with a friend, and 12 percent co-bought with a relative.[2] Affordability was a top reason cited for buying a home together.[3]

Co-Ownership Challenges and Legal Considerations

While co-ownership offers many benefits, it also comes with potential challenges.

Even the strongest relationships can be strained by the pressures of shared living and financial responsibilities. In addition to disagreements over lifestyle choices, finances, and property maintenance that may arise in a co-ownership situation, owning a home with a nonspouse can raise legal issues.

Expectations should be set from the start of the co-owning relationship—ideally, in a written agreement—and regularly communicated throughout it. To ensure a successful co-ownership experience, it is essential to have open and honest discussions with your potential co-owner(s) about the following:

  • Financial contributions. How will the down payment, mortgage, taxes, insurance, and maintenance costs be divided? Will there be a joint account for these expenses? What will happen if one person cannot meet their financial obligations?
  • Exit strategy. What happens if one co-owner wants to sell their share of the property? Will the other owner(s) have a right of first refusal? How will the property be valued?
  • Death or incapacity. How will the property be handled if one co-owner dies or becomes incapacitated (unable to manage their affairs)? Does the ownership structure align with each co-owner’s estate plan goals?
  • Usage and responsibilities. What is the property’s intended use? Will it be a primary residence, a vacation home, or an investment property? How will household chores, maintenance, and repairs be divided?
  • Dispute resolution. What mechanisms will be in place to resolve disagreements or conflicts?

How to Address Potential Co-Ownership Issues

The deed to a property is a legal document that can be instrumental in addressing possible legal and other issues in a co-ownership scenario. It names the co-owners and how they hold title to the property, but it might not address more complex co-ownership issues, such as rights and responsibilities for maintenance costs, how decisions about the property will be made, and a dispute resolution process.

A deed, combined with a more comprehensive co-ownership agreement, should be written to mitigate foreseeable conflicts and protect your interests. The agreement should also be reviewed frequently and updated whenever a co-owner’s circumstances change.

Establishing Ownership Structure

Before buying a home with someone other than a spouse, understanding your options for joint ownership is important. The rules can vary by state, so consulting an experienced attorney can help you make the best choice for your situation. Once selected, the ownership structure needs to be reflected on the property deed.

  • Joint tenancy with rights of survivorship. Under joint tenancy, each co-owner has an equal and undivided interest in the property. Upon the death of one owner, their share automatically passes to the surviving owner. This arrangement is common among married couples and close family members.
  • Tenancy in common. Each co-owner in a tenancy in common holds a certain share of the property, which can be equal or unequal. If the deed does not specify percentages, the co-owners are considered to have equal ownership. When one owner dies, their share passes to their beneficiaries based on their will or to their family members according to state intestacy laws. Tenancy in common offers more flexibility, in particular for co-owners who are not spouses or close relatives, such as two families purchasing a second home together.

Defining Responsibilities and Rights

Clearly defining each owner’s rights and responsibilities is crucial to avoid future conflicts and ensure smooth property management.

  • Financial obligations. To avoid disputes over who pays for what, a co-ownership agreement should outline each co-owner’s financial responsibilities, such as contributions to mortgage payments, property taxes, insurance, and maintenance costs.
  • Usage and access. If the property is a vacation home or investment property, the agreement can specify how the co-owners will share usage and access. Points to address include scheduling, allocation of time, and rules regarding guests.
  • Maintenance and repairs. The agreement may outline division and management of maintenance and repair responsibilities. Each co-owner can be assigned specific tasks, and the agreement can establish a joint fund for these expenses.

Addressing Potential Conflicts

A strong co-ownership agreement should also outline how to resolve disputes.

  • Dispute resolution. A dispute resolution clause can require the co-owners to attempt mediation or arbitration to resolve disputes before resorting to contentious and costly litigation.
  • Buyout provisions. The agreement can outline a process for one co-owner to buy out the other’s share if the other owner wishes to exit the co-ownership arrangement. Key terms to include in a buyout provision are right of first refusal, valuation methods, and payment terms.
  • Sale or transfer of ownership. Conditions for selling the property, such as requiring unanimous consent from the co-owners or establishing a process for handling disagreements about selling, are best addressed before purchasing the home.

Protecting Individual Interests

Consider adding provisions to your co-ownership agreement that safeguard each person’s individual interests.

  • Liens and encumbrances. The agreement should clearly state that each co-owner is responsible for their own debts and that the ownership interest of one co-owner cannot be used as collateral for the other co-owner’s individual loans. This provision helps to protect co-owners from being held liable for others’ financial obligations.
  • Partition action. In cases where co-owners cannot agree on major decisions (e.g., selling the property), the agreement can contain a provision allowing for a partition action, a legal process that allows the court to divide the property or order its sale, providing a resolution when co-owners reach an impasse.

After a deed has been recorded, it cannot be easily changed. To change the contents (e.g., names, ownership structure, ownership percentage) of the original deed, it is necessary to prepare and record a new deed, which requires the consent of all parties involved.

Home Co-Ownership and Estate Planning

Estate planning takes on added importance when you buy a home. Your estate plan should take the long view on homeownership and address the following points:

  • If you own the property as tenants in common, your will should explicitly state who inherits your share of the property. You should also discuss with your co-owner to whom their share of the property will pass at their death.
  • In the case of joint tenancy with rights of survivorship, your share automatically transfers to the surviving co-owner. However, it is still advisable to address the property in your will and clarify your intentions in case of simultaneous death or other unforeseen circumstances.
  • Placing your interest in the property in a trust can avoid the court process known as probate, create a smoother transfer of ownership, and allow greater control over how the property is handled after your death. You can specify conditions in your trust, such as requiring the surviving co-owner to buy out your share from the trust or dictating how the property should be used or managed.
  • Your estate plan can include provisions to address potential disputes among co-owners after your death. For example, you could designate a neutral third party to mediate disagreements or outline a process for selling the property if co-owners cannot reach an agreement.
  • If you own the property as tenants in common and leave your share to multiple beneficiaries, your estate plan should describe how that share will be divided or managed to avoid conflicts among your beneficiaries.
  • Life insurance can give financial security to your co-owner in the event of your death. The death benefit can be used to cover your share of the mortgage, buy out your share of the property, or serve as a source of income or collateral for a loan.
  • Discuss your estate plans with your co-owner so they understand your wishes and you can coordinate your plans as much as possible to prevent surprises and minimize potential conflicts after your death or incapacity. Regularly review and update your estate plan, especially after major life events or changes in your co-ownership agreement.

Homeownership continues to be a key component of the American dream, but it can become more complicated when you own a home with someone other than a spouse. Addressing co-owned property in legal documents removes as much risk as possible from the homebuying equation and sets the stage for a partnership that can benefit you now and your beneficiaries later.

Get in touch with our legal team to discuss how we can help you realize the dream of homeownership.


  1. Manny Garcia, Buyers: Results from the Zillow Consumer Housing Trends Report 2023, Zillow (Aug. 23, 2023), https://www.zillow.com/research/buyers-housing-trends-report-2023-32978. ↩︎
  2. Id. ↩︎
  3. Id. ↩︎