Your College Student’s Digital Life: The Hidden Estate Planning Gap Nobody Talks About

When a child is preparing to leave for college, both the student and the parent may face a period of uncertainty. For many students, college is their first experience living independently. That independence extends beyond just living away from home. It may include having new financial accounts, credit cards, electronic devices, school portals, and online services outside the family’s shared digital environment.

While parents are focused on the tuition, housing, and dorm room essentials, they may overlook important legal changes. Once a student turns 18 or attends a postsecondary institution at any age, parents generally no longer have an automatic right to access the student’s education, medical, financial, or digital information.

Letting go is part of the transition, but an adult student can still authorize trusted individuals to assist them in an emergency. A carefully prepared plan may include a financial power of attorney, healthcare documents, appropriate privacy releases, and specific authority addressing digital assets and accounts. Although such documents cannot guarantee access in every situation, they can make it easier for designated individuals to respond when help is needed.

The Access Problem: What Happens When Parents Need to Step In 

Every year, millions of first-time freshmen begin college in the United States. They are typically already legal adults or close to being legal adults. For many, college is their first real foray into “adulting.” 

That independence comes with a learning curve. Parents often worry that their first-year college student is eating differently, sleeping less, or spending more money as they adjust to life on their own without parental supervision. However, another concern for parents should be what happens when their college student gains digital independence but then loses a device, gets locked out of an account, misses an important notice, or faces an emergency that they cannot help manage.

  • Logistical lockout. Today’s college students may physically live on campus, but their banking, billing, payments, and leases exist almost entirely in the cloud. A parent cannot simply call customer service and take over an account that has been flagged for unusual activity, locked because of a forgotten password, or disrupted by a payment issue. Financial institutions and service providers may refuse to speak with a parent who lacks authorization, even though the parents may fund the account.
  • Lost phone domino effect. For many students, a smartphone is the digital key that unlocks nearly every part of their daily life. Losing that device can mean losing access to banking apps, school portals, email, password recovery tools, authentication codes, and location services. Password resets, backup codes, or account recovery options that are tied solely to the student’s phone or email account can leave parents with no immediate way to help from afar.
  • Student-only authentication loop. Universities increasingly protect student portals with school email accounts, mobile verification, and two-factor authentication. Such portals can contain tuition bills, housing information, financial aid notices, academic records, health center communications, and other crucial information that parents may need in an emergency. Parents may not discover that they have been cut off from these systems until an emergency arises: the student becomes incapacitated, is hospitalized, or is otherwise unable to grant access. 
  • Emergency communication conundrum. Parents may assume that they can simply call and get answers if their college student faces a crisis. But once the student is a legal adult, institutions such as hospitals, campus health centers, schools, and banks may be limited in what they can share or discuss. Without the right legal documents and access arrangements, parents may know that there is a problem but remain unable to obtain information or take action.

Where Legal Documents Fall Short 

College students often send their parents contradictory signals, declaring their independence one moment, then asking for financial help the next. They want to assert that they have grown up, but at the same time, send reminders that they have not yet fully launched.

Mixed messages between parent and child can be a two-way street. Parents may still need to step in, and they may understand that legal documents are needed before they can help. But documents alone do not solve every problem. Estate planning is also about access to information, not just authority on paper.

Certain crises can be easier for parents to handle when the right documents are in place. What is written on paper should align with what was discussed in advance, bringing together the legal and practical information that parents may need to use their authority effectively.

  • Medical emergency while away from home. A Health Insurance Portability and Accountability Act (HIPAA) authorization (which allows medical providers to share information with a named person) or a healthcare power of attorney can allow parents to communicate with medical providers and make decisions if their student is unable to express their wishes. But those documents may not tell parents where the student keeps their insurance card, what medications they take, who their regular physician is, how to access the campus health portal, or whom to contact locally in an emergency.
  • Financial account lockouts. With a financial power of attorney, parents may be authorized to assist with money-related tasks. To do so, they will also need to know which bank, credit card, payment app, landlord, or school billing system is involved, as well as how rent or tuition is paid, where statements are sent, and whether the student has backup access, recovery codes, or a trusted contact on file.
  • Identity verification issues in a crisis. A legal document showing that a parent has authority to assist does not answer the verification question. Parents also need account numbers, recovery email addresses, device passcodes, backup codes, responses to security questions, or the contact information for the appropriate office or provider. Lacking such information, they may be authorized to help in theory but be delayed or blocked in practice.

There are advantages to having everything spelled out in a physical document. But in an environment where digital access has largely replaced physical access and distance can create a false sense of connectedness, families may need extra safeguards for the gap between staying in touch and actually being able to help. 

Giving Estate Planning the “College Try”

College is a transitional period that resembles adult life, but often without all of the real adult responsibilities. However, estate planning attorneys recommend that every adult have a basic estate plan, even students who have just become adults. Meeting with an attorney before a child leaves for college can educate both parents and children about necessary documents and how legal authority, digital access, and emergency information should work together, so that their transition into adulthood is smooth and secure. 
Making Sense of Per Stirpes, by Representation, and Per Capita Distributions

“That’s not fair!” is a common child’s refrain as they advocate for themselves or express what they feel to be unjust. This pursuit of fairness, however, often follows families into adulthood, and it can resurface with real consequences when an estate plan is on the table. 

Ideas about fairness often influence family dynamics and may continue when accounts and property must be divided after a death. Estate planning documents and state laws use several methods to determine how property passes among descendants. Per stirpes, by representation, and per capita are terms commonly used to describe how a deceased beneficiary’s share is allocated among their surviving beneficiaries.

The precise meaning and operation of these terms can vary by state. An estate planning document may also define or modify the distribution method it uses. It is therefore important to review the specific language of the governing document rather than relying solely on the label.

Consider a simple example in which a parent leaves property in equal shares to their children. If all the children survive the parent, each child generally receives an equal share. The distribution method becomes especially important if one of the children dies before the parent but leaves descendants, such as their own children. Depending on the language of the document and applicable state law, that deceased child’s share may pass to their descendants, be reallocated among the surviving children, or be divided in another specified manner.

The differences among per stirpes, by representation, and the various forms of per capita distribution are most easily understood by examining how each method treats the share of a beneficiary who does not survive the testator.

Per Stirpes Distribution

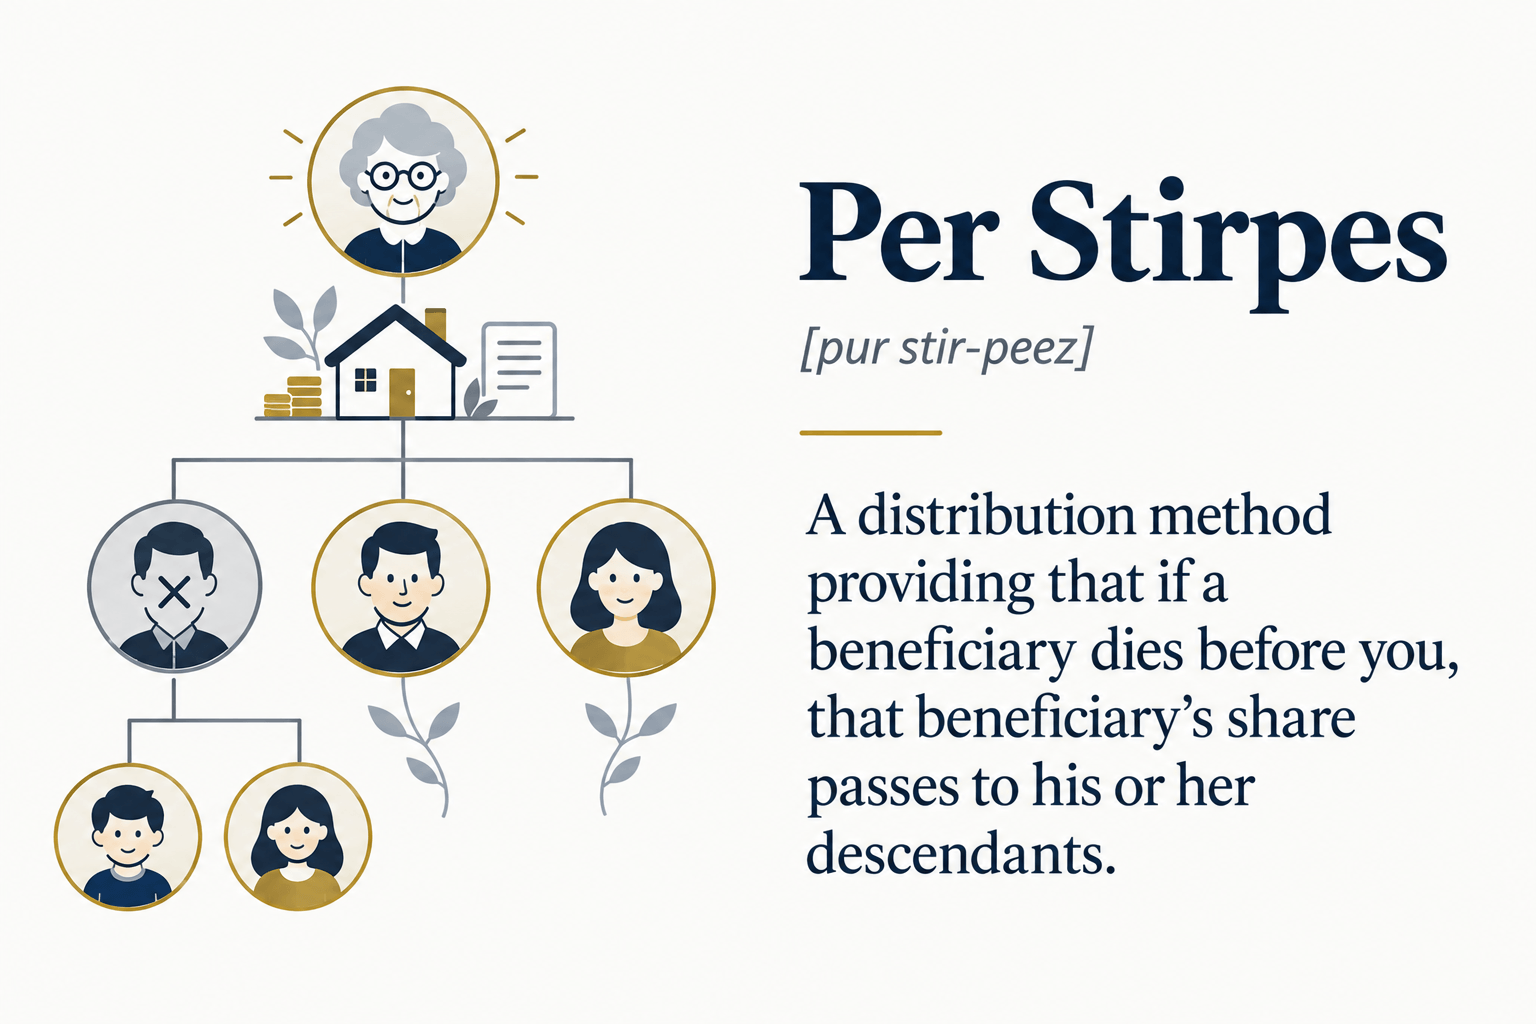
The Latin term per stirpes means “by roots” or “by branch.” Under a traditional per stirpes distribution, the estate is divided into shares at the children’s generation. If a child has died before the person whose estate is being distributed, that child’s share passes down that child’s branch to their surviving descendants.

Consider the following example. Arthur has two children, Becky and Carl. Becky has four children, and Carl has one child.

If Becky and Carl both survive Arthur, each receives one-half of Arthur’s estate.

If Becky dies before Arthur and leaves four surviving children, Becky’s one-half share passes to her children. Becky’s four children divide that share equally, so each receives one-eighth of Arthur’s estate. Carl receives his one-half share.

Becky Predeceases Arthur (Carl Survives)

RecipientShare of Estate
Each of Becky’s four children1/8
Carl1/2

If both Becky and Carl die before Arthur but leave surviving descendants, each child’s one-half share continues down that child’s respective branch. Becky’s four children divide her one-half share, receiving one-eighth each. Carl’s only child receives Carl’s entire one-half share.

As a result, Arthur’s five grandchildren do not receive equal shares. Each grandchild in Becky’s branch receives one-eighth, while the grandchild in Carl’s branch receives one-half. The distribution preserves equality between Arthur’s two family branches rather than equality among all five grandchildren.

The precise operation of a per stirpes distribution may vary under state law and the governing document’s language.

Both Becky and Carl Predecease Arthur

RecipientShare of Estate
Each of Becky’s four children1/8
Carl’s only child1/2

The proportions allocated to each branch remain the same as in the prior example. Under traditional per stirpes distribution, Arthur’s estate is first divided into equal shares at his children’s generation. Becky’s branch receives one-half, and Carl’s branch receives one-half. Each branch’s share then passes to the surviving descendants within that branch.

If one of Becky’s children also dies before Arthur but leaves surviving descendants, that child’s one-eighth share would generally continue down that child’s branch and be divided among their descendants. This process can continue through later generations.

Per stirpes distribution, therefore, preserves equality between the original family branches, even when the number of surviving descendants in each branch differs. The precise result remains subject to the governing document and applicable state law.

By Representation Distribution

In a by representation distribution, descendants generally take the share that their deceased ancestor would have received if still alive. Because the precise method of dividing shares may vary under applicable state law or the governing document, the controlling definition should always be confirmed.

If one of Arthur’s children survives him, that child receives a share at the children’s generation. The surviving child’s descendants generally do not receive a separate share because their parent is alive to inherit.

Now consider what happens if both Becky and Carl die before Arthur. Because neither child survives, the distribution moves to the grandchildren’s generation. All five grandchildren are members of the same generation, so they divide Arthur’s estate equally. It does not matter that four grandchildren descend from Becky and only one descends from Carl.

Both Becky and Carl Predecease Arthur

RecipientShare of Estate
Each of Becky’s four children1/5
Carl’s only child1/5

Under the traditional per stirpes approach described earlier, Becky’s branch would receive one-half of the estate and Carl’s branch would receive the other half. Under the by-representation method illustrated here, all five grandchildren receive equal one-fifth shares.

Because states and estate planning documents may define by representation differently, the governing law and the document’s specific language must be reviewed to determine the intended distribution.

Per Capita at Each Generation Distribution

The Latin term per capita means “by the head.” A trust may direct the trustee to “distribute the trust property per capita at each generation to my then-living descendants.”

Under this method, the estate is first divided into shares among the closest generation that contains at least one living descendant. Each living descendant in that generation receives a share. The shares allocated to deceased members of that generation who left surviving descendants are then combined and divided equally among the eligible descendants of the next generation.

Assume that Arthur has three children: Becky, Carl, and Diane. Becky has four children, Carl has two, and Diane has one. Becky and Carl die before Arthur, and Diane survives him.

Arthur’s estate is initially divided into three equal shares among his children’s generation. Diane receives her one-third share directly. Becky’s and Carl’s two shares, totaling two-thirds of the estate, are combined and divided equally among their six surviving children. Each grandchild receives one-ninth of Arthur’s estate. Diane’s child does not receive a share because Diane survived Arthur and receives her own share.

Becky and Carl Predecease Arthur, and Diane Survives

RecipientShare of Estate
Diane 1/3
Each of Becky’s four children1/9
Each of Carl’s two children1/9

The defining feature of “per capita at each generation” is that the shares of deceased beneficiaries at one generation are pooled and divided equally among the eligible descendants at the next generation. This method produces equal shares for descendants at the same generational level who are taking in place of deceased members of the prior generation.

Because terminology varies among states and documents, the specific definition in the governing instrument and applicable law controls.

We Are Here to Help

Each of these distribution strategies attempts to achieve some form of fairness, but what is fair can be subjective. As you make plans for your family, contact our team. We can help you craft a customized plan that you will feel confident about.

Considerations Before You Head South for the Winter

For many snowbirds, cooler weather means it is time to head south. If you are thinking about heading for warmer weather this winter, there are a few things you should consider before hitting the road.

Which state do you consider your home?

If you split your time between two states, it is important to understand the distinction between residency and domicile. These concepts can affect your estate plan, state income taxes, property rights, and eligibility for certain state benefits and exemptions. They may also affect which state has jurisdiction over a divorce, although child custody jurisdiction is generally determined under separate “home state” rules.

You may qualify as a resident of more than one state because each state applies its own residency rules. However, you can generally have only one domicile at a time. Your domicile is the state you consider your permanent or indefinite home and the place you intend to return to when you are away. Determining domicile depends not only on what you say your intentions are but also on your actions and connections to each state.

Splitting your time between states can affect more than your lifestyle—it may also affect your income taxes, estate or inheritance taxes, property-tax benefits, and estate plan. Talk with your tax advisor to confirm that you are filing the appropriate returns in each state and taking advantage of any available tax-planning opportunities. 

State tax rules vary widely. Alaska, Florida, Nevada, New Hampshire, South Dakota, Tennessee, Texas, Washington, and Wyoming do not impose a broad-based individual income tax. However, some of these states tax particular types of income. 

Owning property in more than one state can add another layer of complexity, particularly if one state follows community property rules and the other follows common law property rules. In a community property state, most property acquired by either spouse during the marriage is generally treated as jointly owned, subject to important exceptions. In a common law property state, ownership is generally determined by title and other state property laws, although a spouse may still have marital, homestead, elective share, or other rights in the property.

We encourage you to meet with us to ensure that your estate plan accounts for the laws of each state in which you live or own property.

Have you reviewed your estate plan lately?

Life changes, sometimes without much warning. Before you head out for the season, take time to pull out your estate planning documents and ensure that they still reflect your wishes, both during your lifetime and after your death. 

Ask yourself the following questions:

  • Are your chosen decision-makers still the right ones? These individuals may include your trustee, personal representative or executor, guardian for a minor child, and the agents named in your financial or medical powers of attorney. Are they still willing and able to serve?
  • Are your beneficiaries up to date? Confirm that everyone you have named is still living. Is there anyone new—family, friends, or charities—that you would like to include? Would you like to change how much someone receives or how they receive it?
  • Do your beneficiary designations match your overall plan? Retirement accounts and life insurance policies pass directly to whoever is named on the account, regardless of what your will or trust says. Make sure that these designations line up with the rest of your estate plan.
  • Can your agent move you to another state if needed? If a health issue leaves you unable to make decisions for yourself, does your named agent have the authority to relocate you—for example, to be closer to family?

If you may need help managing finances or completing transactions while you are away, check when your financial power of attorney becomes effective. Depending on the document and the law of the state in which it was created, it may be immediate or springing.

  • An immediate power of attorney generally becomes effective as soon as it is properly executed. Your agent can act on your behalf even while you remain fully capable of managing your own affairs. This setup can be helpful if you want assistance while traveling. You do not give up your own authority simply because your agent is also authorized to act.
  • A springing power of attorney becomes effective only after a specified event occurs—typically the determination that you are unable to manage your financial affairs. The document and applicable state law control who must make that determination and what evidence is required. Some states restrict or do not recognize newly executed springing powers of attorney.

Where both options are available, neither is inherently better. The right choice depends on your circumstances, your level of trust in the person you appoint, and your applicable state law. It is important to know when your agent’s authority begins and whether your power of attorney is durable, meaning that it remains effective if you later become incapacitated. These details can affect how quickly your agent can step in when assistance is needed.

While reviewing your existing estate plan, it is also a good time to check whether it includes everything you need. If your current plan relies only on a will, you may want to consider adding a revocable living trust, especially if you own property in more than one state. Without a trust, your loved ones may have to go through probate (the court process for settling an estate) in each state in which you own property. A trust can consolidate your property under one roof, helping your family avoid multiple, overlapping probate proceedings, saving significant time, cost, and stress when settling your affairs. 

Are your estate planning documents compliant in both states?

Estate planning laws vary by state, particularly those governing documents such as financial powers of attorney and healthcare directives. Many states provide statutory or state-approved forms for these documents, although using those forms may not be required.

A document that is valid in one state will generally be honored in another. But in a medical emergency, speed matters, and medical providers are often quicker to act on a form they recognize. An unfamiliar document from another state may cause hesitation or delay while it is reviewed, even if it is technically valid. 

For this reason, we recommend having an attorney licensed in your second state review your existing documents. If needed, they can prepare a second financial power of attorney and healthcare directive tailored to that state’s format, giving you one less thing to worry about if you ever need care while you are away. 

As you prepare for your upcoming travel, call us. We are here to answer any questions to ensure that you are properly protected no matter where your travels take you this season. 

Choosing the Right People for the Right Roles in Your Estate Plan

If you are single, choosing the people who will serve in your estate plan is far more than a formality. It is one of the most consequential planning decisions you will make.

Married individuals often rely on a spouse to act during an emergency, manage financial or healthcare decisions, and handle practical matters after death. Single individuals do not have that automatic decision-maker, making intentional selection especially important.

Although well-drafted documents are essential, the people you appoint will ultimately carry out your wishes. Choosing capable, trustworthy, and available individuals can determine whether your plan operates smoothly or leads to unnecessary stress, conflict, and delay during an already difficult time.

Choosing Well, Not Just Choosing Someone

The difference between simply naming someone and selecting the right person is often that person’s ability and willingness to follow through. In practice, serving in an estate planning role may require the following:

  • Responding promptly to time-sensitive calls and emails
  • Managing important documents and deadlines
  • Making difficult decisions under stressful circumstances
  • Communicating with family members or friends who may disagree

For single individuals, the challenge is often deciding who can realistically carry out these duties. The right choice may be a sibling, a longtime friend, an adult niece or nephew, or another trusted person who is willing, capable, and available to serve.

What Each Role Demands

A strong estate plan may involve several distinct roles, each requiring different skills and responsibilities. Although one person may be capable of serving in multiple roles, it is generally best not to assign every role to the same individual by default.

Executor or personal representative. This person handles practical and legal steps after death—gathering documents, paying final bills, and helping to distribute property.

What to look for in an executor or personal representative:

  • Trustworthiness, sound judgment, and integrity
  • Strong organizational skills and attention to detail
  • Persistence in completing paperwork and meeting deadlines
  • Availability to communicate with attorneys, accountants, beneficiaries, and financial institutions
  • Ability to remain calm and impartial when disagreements arise
  • Willingness to seek professional assistance when needed

Trustee. This person manages trust assets, follows the trust’s instructions, keeps records, and communicates with beneficiaries.

What to look for in a trustee:

  • Financial responsibility and careful attention to detail
  • Honesty, impartiality, and respect for the trust’s instructions
  • Ability to evaluate distribution requests and make difficult decisions
  • Willingness to maintain accurate records and provide required reports
  • Ability to manage investments prudently or retain qualified advisors
  • Strong communication skills, particularly when beneficiaries have competing interests
  • Long-term availability and willingness to accept the responsibility involved

Financial power of attorney agent. This agent may pay bills, manage accounts, deal with institutions, and handle benefits if you are alive but are unable to manage your affairs.

What to look for in a financial power of attorney agent:

  • Integrity and unquestionable trustworthiness
  • Financial responsibility and comfort handling money and paperwork
  • Sound judgment and attention to detail
  • Willingness to maintain complete and accurate records
  • Availability to respond promptly when action is required
  • Ability to work effectively with financial institutions and professional advisors
  • Commitment to acting in your best interests and following the authority granted

Healthcare agent. This agent makes medical decisions if you cannot, advocates for your wishes, and communicates with healthcare providers.

What to look for in a healthcare agent:

  • Emotional steadiness during stressful or uncertain situations
  • Willingness to ask questions and understand medical information
  • Assertiveness when advocating for your wishes
  • Availability and ability to respond quickly in an emergency
  • Comfortable discussing serious illness, end-of-life care, and other sensitive matters
  • Ability to communicate and collaborate with healthcare providers and loved ones
  • Commitment to following your stated preferences, even if they differ from the agent’s personal views

The Conversation You Need to Have

One of the most important—and frequently overlooked—steps for single individuals is speaking with each person named in the estate plan to confirm that they understand the role and are willing to serve.

If someone learns that they have been appointed as an executor, trustee, financial agent, or healthcare agent only after a medical crisis or death, they may feel unprepared, delay taking action, or decline to serve. A thoughtful conversation in advance can prevent confusion and help ensure that the plan works as intended.

The conversation should address the following topics:

  • The role you would like the person to serve and its general responsibilities
  • Why you believe the person is well suited for the role
  • Whether the person is willing and able to serve
  • Any questions, limitations, or concerns the person may have
  • Where your estate planning documents and other essential information will be stored
  • How to access account information, professional contacts, and emergency instructions
  • Whom you have named as a successor or backup if the person cannot serve
  • Whether and how the person may be compensated or reimbursed for expenses

Make It Easier for Them to Succeed

Many single adults worry about placing a burden on others. One of the best ways to reduce that burden is to organize the information your decision-makers will need. A secure paper or digital “in case of emergency” file may include these items:

  • The location of your will, trust, powers of attorney, and healthcare directives, along with instructions for accessing them
  • Contact information for your attorney, financial advisor, accountant, and other key professionals
  • A current list of accounts, recurring bills, insurance policies, and other important financial information
  • Contact information for healthcare providers and a summary of your healthcare preferences
  • Information about your home, pets, digital assets, and other matters requiring immediate attention

Protect sensitive information and let your decision-makers know how to access it when necessary. Review the file periodically so that it remains accurate and useful.

When It Is Time to Revisit

Revisiting your choices does not mean that your plan has failed. It means that your plan is evolving with your life. Regular reviews may be especially important for single individuals because their closest relationships and support networks can change over time.

Consider reviewing your plan in the following circumstances:

  • A close relationship ends or materially changes.
  • Someone you named moves away, becomes unavailable, experiences health concerns, or is no longer a suitable choice.
  • You purchase a home, receive an inheritance, start or sell a business, or experience another significant financial change.
  • You move to another state.
  • Your family structure or support network changes.
  • Your wishes regarding healthcare, property, or beneficiaries change.
  • Several years have passed since your last review.

Even without a major life event, consider reviewing your plan with your estate planning attorney every three to five years.

Your Plan Should Reflect Your Life as It Is, Not as It Was

For single adults, the people named in an estate plan should reflect current relationships, practical availability, and genuine trust. Keeping those appointments current is an act of care for both you and the people you have asked to serve. It helps ensure that your wishes can be carried out while giving your decision-makers the information and authority they need to act confidently during a difficult time.

If you are unsure whether your current choices still fit your life, we can help you evaluate your options, select appropriate backups, and update your documents to reflect your circumstances today.

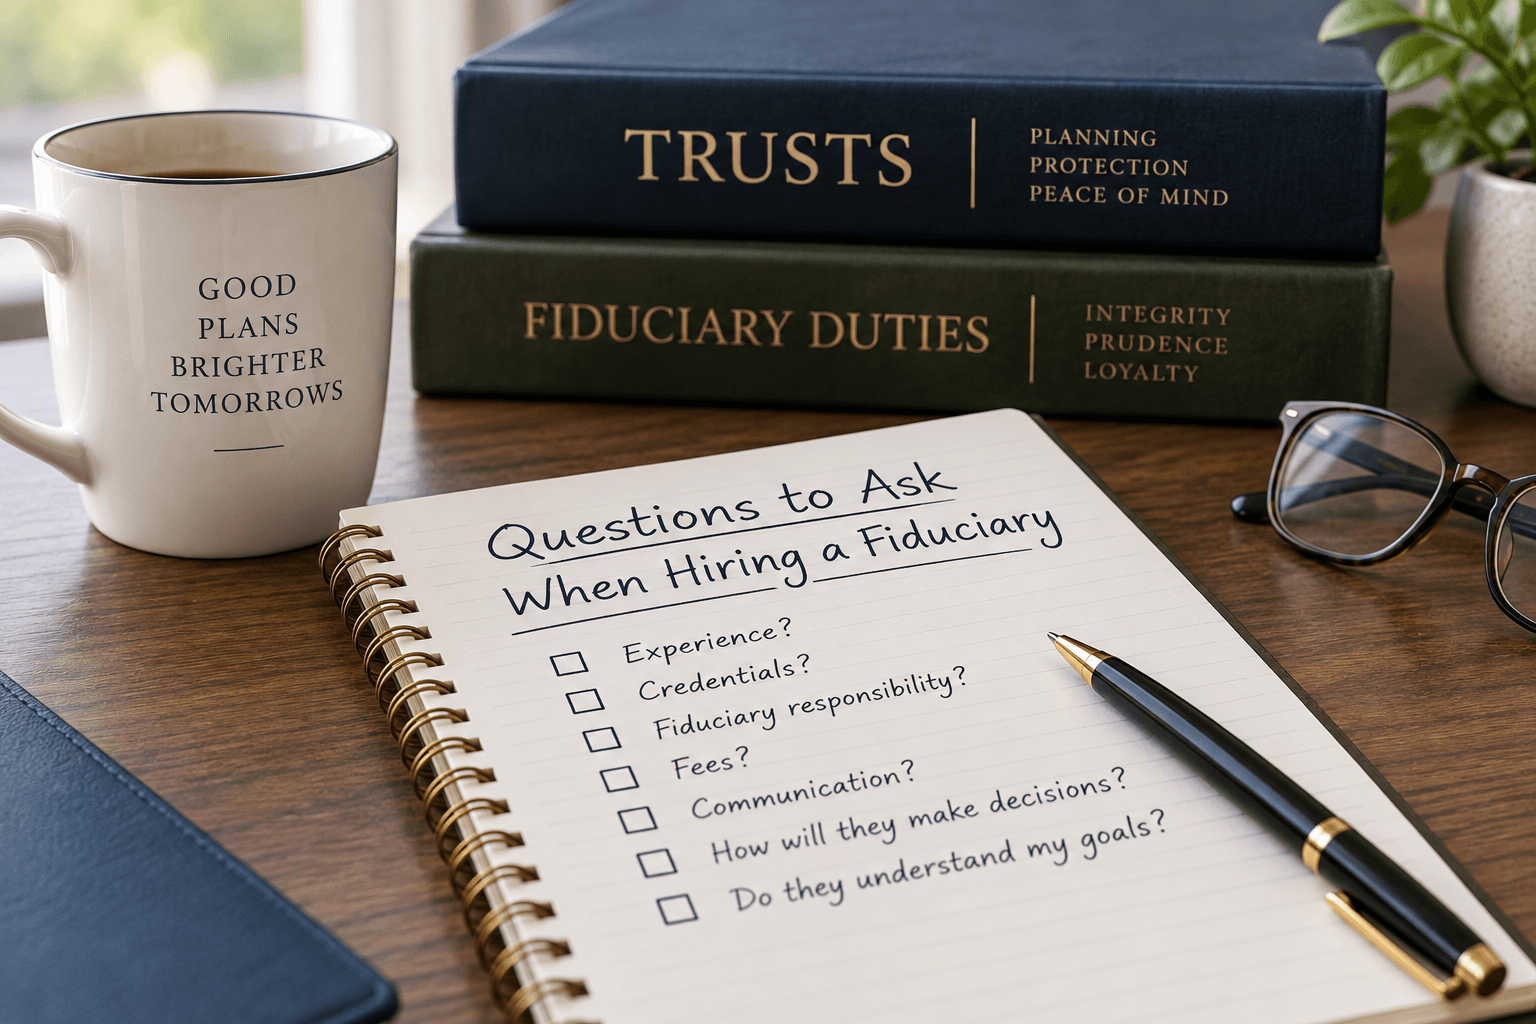
Questions to Ask When Hiring a Fiduciary

A comprehensive estate plan does more than direct who will receive your money and property after your death. It also provides instructions for managing your affairs during your lifetime and identifies the people who will act for you if you are unable to act for yourself. An effective plan generally does the following:

  • Outlines your wishes for managing and distributing your money and property during your lifetime and after your death
  • Documents your healthcare preferences if you become unable to make or communicate medical decisions
  • Designates trusted individuals to carry out financial, legal, and healthcare decisions on your behalf

Choosing these decision-makers can be difficult. Family conflict, geographic distance, a lack of available relatives, or an unconventional support network may mean that a family member or close friend is not the best choice. Even someone you trust personally may lack the time, experience, organization, or willingness required to serve effectively.

Many of the individuals appointed to manage your property or financial affairs—such as trustees, personal representatives, and agents under financial powers of attorney—serve as fiduciaries. A fiduciary has a legal duty to act in accordance with the governing document and applicable law, including duties to act loyally, carefully, and in the interests of the person or beneficiaries they serve.

When a suitable friend or family member is unavailable, hiring a professional fiduciary may provide experience, neutrality, and continuity. However, not every professional offers the same qualifications, services, or fee structure. Asking the right questions can help you determine whether a prospective fiduciary is qualified, trustworthy, and well suited to carry out your wishes.

Financial Decision-Makers

  • Executor or personal representative. This person administers your estate after your death. They collect and manage estate assets, pay valid debts and expenses, complete required filings, and distribute the remaining property to your beneficiaries or trustee according to your estate plan and applicable law.
  • Successor trustee of a revocable living trust (if applicable). This person takes over management of the trust when the current trustee dies, resigns, or becomes unable to serve. Depending on the circumstances and the trust’s terms, the successor trustee may manage and use trust property for your benefit during your lifetime and distribute the remaining property to your beneficiaries after your death.
  • Agent under a financial power of attorney. This agent conducts authorized financial and legal transactions on your behalf, such as managing accounts, paying bills, or signing documents. The scope of the agent’s authority and when that authority becomes effective are governed by the power of attorney and applicable state law.

When selecting an agent to handle your financial transactions, several options may be available to you beyond family and friends:

  • Ask if your bank or financial institution has a trust department. Because they are already familiar with managing your accounts, they may be a good fit to step in and assist you if needed.
  • Interview a private trust company that specializes in managing money on behalf of individuals. They are likely well equipped to handle the administrative tasks associated with being a financial decision-maker.
  • Consider asking your certified public accountant (CPA) or financial advisor if they are willing to act on your behalf or if they know someone who can.

When interviewing potential candidates, consider asking the following questions:

  • How do you charge for your services? Ask whether fees are hourly, based on a percentage of the assets, subject to a minimum, or calculated another way. Also inquire about additional expenses so that you can understand how the total cost may affect your estate or beneficiaries.
  • How do you document the transactions you conduct, and who may access those records? Careful recordkeeping and appropriate transparency help ensure accountability while protecting sensitive financial information.
  • How long does it typically take to administer an estate or trust of this size and complexity? Although timing depends on the circumstances, the answer can help you evaluate the fiduciary’s experience, workload, and approach to resolving matters efficiently without sacrificing accuracy.
  • How often do you communicate with the beneficiaries and my family members? It is important that everyone is on the same page and that the lines of communication remain open, even at your death, to help avoid potential conflicts after you have passed away.
  • Do you require specific provisions in the estate planning documents or any additional paperwork before agreeing to serve? Your estate planning attorney should review these requirements to ensure that your documents grant the necessary authority and will operate as intended when the fiduciary takes over.
  • What have been your most successful and most challenging experiences administering an estate or a trust? The response may reveal how the fiduciary approaches difficult situations, communicates with beneficiaries, resolves conflicts, and defines a successful administration. It can also help you determine whether the professional’s experience and working style align with your needs.

Personal Care Decision-Makers

These roles often feel like the most difficult to fill because you are asking someone to look after your safety and welfare as well as that of any pets you may have. Accordingly, each role has unique considerations:

  • Agent under a medical power of attorney. This agent makes or communicates your medical wishes if you become unable to make or communicate them yourself. In addition to appointing an agent, consider completing an advance directive or living will with the assistance of your estate planning attorney. These documents can communicate your treatment preferences to your agent and healthcare providers.

You may also wish to prepare a letter of instruction explaining, in your own words, the types of treatment you would or would not want. Although such a letter may not carry the same legal authority as an advance directive, it can provide valuable guidance when difficult or unexpected decisions arise.

If you do not have a suitable family member, you may consider appointing a trusted friend or, where permitted, a qualified professional. State law may prohibit certain individuals, including some healthcare providers or employees of healthcare facilities, from serving unless an exception applies.

  • Caretaker for your pet. This person provides a safe and loving home for your pet if you become unable to care for them. Because the law generally treats animals as personal property, simply expressing your wishes may not be enough. Speak with the proposed caretaker in advance to confirm that the person is willing and able to serve, and consider providing funds and written instructions for your pet’s ongoing care.

If no family member or friend is suitable, certain animal welfare organizations, veterinary programs, or foundations may be able to care for your pet or help identify an appropriate permanent home. Any arrangement should be confirmed with the organization in advance and properly incorporated into your estate plan.

When interviewing potential candidates for your personal care decision-makers, consider asking the following questions:

  • Do you charge for your services? Some professionals and organizations charge fees, while friends or family members may not. Understanding the anticipated cost allows you to set aside sufficient funds and determine how those expenses will be paid.
  • When and how should you be contacted if your assistance is needed? Because you do not know when you will need their assistance and will likely not be the one contacting them, it is important that you have an easy way for someone else to contact them in an emergency.
  • Is there additional information or paperwork needed to carry out your role? Confirm that the person or organization has, or knows how to access, the necessary legal documents, contact information, medical preferences, pet-care instructions, and other relevant records before an emergency occurs.

Uncertainty about whom to appoint to these important roles can delay the estate planning process, but it should not prevent you from moving forward. We can help you evaluate your options, identify appropriate decision-makers, and create a plan that protects you and those you care about. Contact us to discuss how to put trusted decision-makers in place before they are needed.

The Invisible Estate: Do Not Let Your Loyalty Points Die with You

If cash is king and credit is queen, digital rewards points may just be the wildcard of your household finances. While cash represents immediate purchasing power and credit offers leveraged liquidity, rewards points function as a flexible currency that can supplement spending. But unlike cash and credit, they vanish when you die.

Most people do not include rewards points and loyalty program credits in their cash flow calculations, even when they have a large stockpile. These points and credits rarely make it into an estate plan either, even though their accumulated worth may represent real financial value. To keep your points from expiring when you do, they should be inventoried, documented, and directly addressed in your estate plan. 

The Legal Gray Zone

When you log into a banking or travel app and see a rewards balance, it may look much like a digital bank statement. But your cash and your points live in different legal worlds. Your bank account holds property that you own. Your rewards account generally contains contractual benefits you may use only according to the issuer’s rules. 

The Fine Print 

Loyalty program terms commonly state that points have no cash value, are personal to the member, remain the exclusive property of the issuing company, and may be transferred or redeemed only as the program allows. 

You may not own your points in the same unrestricted way that you own money in a bank account; you may have only a conditional contractual right to use them.

Rewards companies, therefore, have wide latitude over how their programs operate, including the ability to change redemption rates, restrict transfers, impose expiration rules, or close accounts. That latitude is not unlimited: Federal and state consumer protection laws may apply when a company advertises rewards and then unfairly prevents consumers from redeeming them. But the starting point is usually the contract the member accepted upon joining.

Such characteristics make rewards points difficult to classify for estate planning purposes. Although they carry recognizable economic value, they lack the unrestricted ownership and transfer rights associated with cash, securities, or other conventional assets, and that distinction becomes consequential the moment an account holder dies.

Why You Cannot Simply Bequeath a Mile

Because points are seen as contractual agreements and not personal property, a will cannot override the loyalty program’s contract or give an heir rights that the account holder never had. What happens at death, therefore, depends largely on corporate policy. 

  • Strict forfeiture. Some programs prohibit transfers to an estate or beneficiary. For example, Southwest Airlines states that Rapid Rewards points may not pass through an estate, settlement, inheritance, or will. When the account is closed following the member’s death, the remaining points are forfeited. 
  • Discretionary transfers. Other airlines reserve the right to make exceptions. United says that it may, at its “sole discretion,” credit some or all of a deceased member’s miles to an authorized person. American Airlines provides that an AAdvantage account typically terminates at death unless the airline permits otherwise. In these cases, an executor or heir may request a transfer but cannot expect an automatic one as a property right. 
  • Administrative hurdles. Even when a company permits a transfer, it may burden an executor with bureaucratic steps that include submitting a death certificate, proof of authority, account information, and other documentation. Transfer fees or deadlines may also apply.
  • Account closure and forfeiture. Credit card rewards can present an additional problem. Once an issuer has been notified of a cardholder’s death, the credit account may be restricted or closed. Depending on the card agreement and the issuer’s procedures, closing the account may cause unused rewards to expire before the executor knows they are there or has an opportunity to redeem them. 
  • Forced cash conversion. Some programs do not erase the account balance at death. For example, Chase Ultimate Rewards agreements state that points are not the cardholder’s property and cannot pass by inheritance. However, when Chase is notified of a cardholder’s death, the remaining points are automatically redeemed for cash as a statement credit, preserving their cash value for the estate but eliminating the ability to transfer them to airline or hotel partners or for higher-value travel redemptions.
  • Limited unclaimed property protection. Most traditional financial accounts are subject to state unclaimed property laws, which may require dormant funds to be transferred to the state for later recovery. Loyalty points do not always receive the same protection. Some states expressly exclude frequent-flyer miles, merchandise points, and other noncash rewards from their unclaimed property statutes.

The Scale of the Unseen Wealth

Divorce courts have occasionally classified loyalty points accumulated during a marriage as marital property because they provide a measurable economic benefit. That legal recognition hints at just how much value lies within this gray zone.

The numbers are significant: 

  • US consumers earned $47.5 billion in credit card rewards in 2024 and redeemed approximately $43 billion during the year, leaving about $4.5 billion unused or carried forward.
  • Hotel programs also carry enormous obligations. Marriott reported nearly $8 billion in deferred revenue tied to its Bonvoy loyalty program at the end of 2025.
  • Airline loyalty programs dwarf even that: Delta SkyMiles, American AAdvantage, and United MileagePlus were collectively valued at $83.7 billion in 2026. Delta’s program alone was worth $31.7 billion.
  • Gift cards and store credits add another layer. A recent Bankrate survey found that 43 percent of US adults held at least one unused balance with an average value of $244.


Much of this value never gets used. The loyalty industry calls unredeemed rewards breakage—value lost to forgotten accounts, inactivity, expiration rules, or death. A 2026 industry report estimates that 26.2 percent of loyalty points go unspent and 11.9 percent expire before they are used, costing US consumers up to $10 billion in potential savings annually.

That loss is unevenly distributed: The Consumer Financial Protection Bureau found that subprime cardholders forfeit rewards at more than twice the overall rate. Companies account for expected breakage when measuring their outstanding rewards obligations because permanently unredeemed benefits eventually reduce their liabilities. For consumers and their families, that breakage represents value that was earned and never recovered.

Death can quietly become one more path to breakage, and unlike expiration or inactivity, that loss often happens before anyone realizes there was something worth saving.

How to Preserve and Protect Your Loyalty and Rewards Points

To ensure that the value you earned is not erased by expiration dates or corporate account sweeps, take the following steps to shield your loyalty wealth.

Audit and Create a Living Inventory

Treat loyalty points, airline miles, cash-back balances, gift cards, and travel credits with the same care and attention you give to traditional bank accounts.

  • Track your accounts. Compile a list of the loyalty programs you use, including account numbers, approximate balances, and estimated redemption values.
  • Monitor expiration rules. Identify programs with inactivity or expiration provisions. A small qualifying transaction—such as buying a coffee or transferring a nominal block of points—may be enough to keep some accounts active.
  • Update the inventory. Periodically review the list and remove closed accounts, add new programs, and track unusually large balances.

Securely Document Access Information

An executor cannot administer an account that they do not know exists. Access, however, must be balanced with security and privacy. Avoid placing passwords and other sensitive information directly in a will, which may become part of the public probate record.

  • Use secure storage. Keep account credentials and recovery information in an encrypted password manager or another protected digital vault.
  • Provide access instructions. Explain how your executor or another authorized person can locate the inventory and request access through the company’s procedures.
  • Use available legacy tools. When a password manager, email provider, or digital storage service offers emergency access or legacy contact features, consider designating a trusted person.

Brief Your Executor About High-Value Programs

Some programs may transfer balances or permit postdeath redemption when an executor follows their procedures and provides the required documentation. Make sure your executor knows which accounts hold the greatest value and where the supporting information is stored.

  • Flag significant balances. Identify major airline, hotel, credit card, and retail programs that should be checked immediately after death.
  • Document program requirements. Note whether a program permits transfers, discretionary exceptions, postdeath redemption, or no transfer at all.
  • Address digital assets in your estate plan. Work with an estate planning professional to authorize your executor to access and manage digital accounts and electronic records. This authority cannot override a loyalty program’s terms, but it empowers the executor to identify accounts, request information, and pursue any available transfer or redemption rights.

Make Your Invisible Estate Seen

With billions of dollars in rewards going unused or expiring each year, loyalty points are worth a place in the estate planning conversation. 

Your accumulated miles and points represent not only real, calculable wealth, but a significant investment of your money and time. You may miss the chance to use them, but that does not necessarily mean somebody else cannot benefit.

A gift of digital rewards could be a unique way to reward somebody in your estate plan. Making that gift possible, however, requires researching the program rules, documenting your wishes, and giving your executor the authority and information needed to keep the rewards usable.

How to Protect Your Great Ideas or Works for Your Family

Your money, home, and vehicles are not the only assets that should be addressed in your estate plan. You should also consider your intellectual property, including any rights and income associated with it. You do not have to be a famous author, painter, or inventor to own valuable intellectual property that could generate income for your loved ones after you pass away.

Intellectual property generally includes creations and inventions that may be legally protected by copyrights, patents, trademarks, or other rights. Examples include written works, photographs, artwork, music, software, inventions, brand names, logos, and online content. These assets may have significant economic and personal value and require thoughtful planning to ensure that they are properly managed, protected, and transferred.

Take Steps to Protect Your Intellectual Property

Different steps are necessary to legally protect different types of intellectual property. Here are some of the most common types:

  • Copyright protects “original works of authorship” such as books, movies, songs, computer software, photographs, and architectural works. Works do not need to be published to be protected, but publication generally increases commercial value. Copyright exists the moment you create an original work. However, to enforce your copyright in an infringement lawsuit, you must register it with the US Copyright Office. You should also display the copyright symbol (©) to provide public notice. Copyrights generally last 70 years after the creator’s death, though works made for hire or owned by a business are subject to a different rule.
  • Patents are available to anyone who invents or discovers “any new and useful process, machine, manufacture, or composition of matter” or improves upon an existing one. Different patent types exist for different inventions. To be eligible, your invention must not have been publicly disclosed before you file. Before applying, conduct a comprehensive patent search. An attorney or agent can help with the search and prepare your application for filing with the United States Patent and Trademark Office (USPTO), ensuring that your patent provides sufficient protection. Once granted, a utility or plant patent lasts 20 years from the filing date, while a design patent lasts 15 years from the grant date. Utility patents also require periodic maintenance fees; design patents do not.
  • Trademarks are typically brand names and logos that identify and distinguish the goods and services of one source from those of others. Simply using your mark gives you limited legal protection under common law, but only in the geographic area in which you use the mark. State registration extends that protection statewide. For national protection, register your trademark with the USPTO. Before filing, perform a thorough trademark search to confirm that your desired mark—or anything confusingly similar—is not already in use. Use the TM symbol for unregistered marks and the ® symbol once your mark is federally registered, both of which serve as public notice of your claim. A federal trademark has an initial 10-year term and can be renewed indefinitely in additional 10-year increments for a fee. To keep it valid, you must continue using the mark in commerce and actively defend it against infringement.

Include Your Intellectual Property in Your Estate Planning

Including intellectual property in your estate plan can help preserve its value and ensure that the associated rights and income are managed according to your wishes. Before creating or updating your plan, provide your estate planning attorney with a complete inventory of your intellectual property, along with any related registrations, applications, agreements, assignments, licenses, royalty statements, and ownership records.

Copyrights

Of the three types of intellectual property, copyrights require the most careful estate planning, largely because of a unique legal rule that can unravel your intentions if you are not aware of it. 

If you own a copyright, you should specifically address both the title of the original work (i.e., the book, painting, etc.) and the details of your copyright in your will or trust. If your copyright is not specifically mentioned in your will or trust, it will instead pass through a catch-all (residuary) provision covering property you did not address elsewhere. This outcome can create problems because the physical work—the book, the painting, the master recording—and the copyright in that work are legally separate property interests. Without specific instructions, one person could inherit the physical item while someone else inherits the copyright. In addition, depending on how valuable the copyright is, the heirs who inherit it could have a heavier tax burden.

Copyright law also gives creators a right to terminate most transfers or licenses of copyright in their works after a set number of years. After the creator’s death, this termination right passes to a surviving spouse and children. Importantly, this right cannot be waived or signed away in advance, even by contract. Transfers made by will are generally excluded from these statutory termination provisions; however, this does not necessarily mean that a will is always preferable to a trust for transferring copyrights. The appropriate method depends on the nature of the rights, when and how they were transferred, probate considerations, and the creator’s long-term goals. Estate planning and intellectual property counsel should coordinate to determine the best approach.

Patents

Unlike copyrights, patents carry no termination right, so they can be freely transferred by a will or to a trust for the benefit of your loved ones. Transferring ownership to a trust can help avoid the cost, delay, and public exposure of probate. When including patents in your estate plan, ensure that your documents clearly identify the following:

  • the owner of the patent 
  • the patent number
  • those who have the right to license the patent
  • the parties responsible for paying the fees required to maintain the patent

In addition, documentation evidencing the transfer to the new owner should be recorded with the USPTO.

Trademarks

Like a patent, a federally registered trademark may be transferred through a will or trust. A trust may offer advantages, such as continuity of management and probate avoidance, but the appropriate method depends on the owner’s circumstances and goals. Because a trademark generally must be transferred together with the goodwill associated with the business or goods and services it represents, the estate plan should address both the mark and the related business interests.

The executor, trustee, or beneficiary who receives the trademark should record the change in ownership with the USPTO and maintain documentation establishing the chain of title. The new owner must also continue using the mark in commerce, monitor and address unauthorized uses when appropriate, submit required maintenance and renewal filings, and pay applicable fees. Failure to properly use, maintain, or protect the trademark may weaken the owner’s rights or result in loss of the registration.

Royalties

Intellectual property that has been transferred or licensed to another party often generates royalties or other income. Depending on how your estate is structured, those payments could flow directly to your heirs or be directed to a living trust or a trust established at your death. When you pass away, any publishers or other agencies should be notified to direct the payments to the trust or to the loved ones who have inherited the right to receive those royalties. It may also help to name an executor or trustee with expertise in managing intellectual property and the royalties it generates.

Contact Us

Estate planning for intellectual property can be complicated. We can help ensure that the products of your creativity are properly protected and passed on to your family and loved ones in the way you intend. Contact us to achieve your estate planning goals for your intellectual property.

Estate Planning After Remarriage

You may not be able to choose the family you are born into, but you can choose the family you build through marriage, partnership, and the life you create on your own terms. The traditional nuclear family is no longer the default, and biological family ties are no longer always assumed.

Marriage remains its own unique legal institution, with rights and obligations that go far beyond the informal promise of “’til death do us part.” However, it looks very different than it once did—and so do the challenges, particularly when families are blended.

Remarriage offers another chance at love and stability. It also introduces estate planning risks that need to be addressed well before walking down the aisle to say “I do.”

The Modern (Blended) American Family 

Today’s concept of “family” is notable for the absence of a single definition. 

Families are more diverse and less structured than in years past and just as likely to be marked by emotional bonds—cohabitation, co-parenting, and chosen families—as by formal legal ties. 

Research confirms that there is no longer a predominant family form. And while divorce rates remain relatively high, they are closer to 40 percent today—not the widely repeated 50 percent figure based on the peak divorce era of the late 1970s and early 1980s. 

American popular culture introduced the idea of blended families through the television show The Brady Bunch, in which two parents remarried and combined children from prior relationships into a single household. 

When the show first aired in 1969, roughly two-thirds of Americans ages 25 to 49 lived with a spouse and at least one child under 18. By 2021, that figure had dropped to just 37 percent.

Blended families today rarely resemble the Brady household. The category is broad, encompassing any family that includes a stepparent, stepsiblings, or half-siblings, and the structures can vary widely. 

If there is a uniform feature of the modern American family, it is precisely this lack of uniformity.

More than half of US families are now remarried or recoupled in some form. Remarriage after divorce remains the most common path to a blended family, though other types of blended families may form after the birth of a child outside of marriage or following a spouse’s death. 

However families become blended, the US is now a nation in which roughly 17 percent of children under 18 live in a blended family and more than 40 percent of adults have at least one steprelative. 

Rewriting Family and Rewriting Your Estate Plan

Blended families are increasingly the norm, but their normalization does not make their challenges any easier. 

Forming a blended family is rarely as frictionless as The Brady Bunch made it seem. It can take years to build a strong blended family through patience, open communication, and establishing roles and boundaries—and there is no set timeline or formula for success. Each family figures it out in its own way. 

That complexity makes financial and legal planning more important, not less. Marital agreements—prenuptial and postnuptial—may be more useful in blended families than in first-time marriages. While they were once viewed primarily as “divorce insurance,” in the context of a blended family, they function as a foundational estate planning tool, encouraging honest communication about finances and reducing future potential misunderstandings and resentment. 

Some couples may view marital agreements as too extreme or unnecessary. Yet more Americans are using them: The number of couples signing a prenuptial agreement has increased from 3 percent in 2010 to 15 percent in 2022. 

Meanwhile, less than 25 percent of Americans say they have an estate plan. Among those who do, nearly one-quarter have never updated it. 

Remarriages and blended families are rewriting the rules of what it means to be a family. But if estate planning documents are not also rewritten with remarriage in mind, they can introduce legal challenges that rival the personal and emotional ones. 

The “I Do” Danger Zone: Remarriage Estate Planning Pitfalls 

When a family blends, the legal margins for error can become less clearly defined. What may have been a minor oversight in one marriage can become a catastrophic legal battle in a subsequent one. 

Here are some common ways an estate plan—new or old—can become as outdated as the concept of the traditional nuclear family.

Outdated Documents

Outdated beneficiary designations are one of the most frequent and preventable estate planning oversights following a remarriage. In many jurisdictions, assets such as 401(k) plans, individual retirement accounts, and life insurance policies are nonprobate assets, meaning that they pass directly to the person named on the beneficiary designation form, regardless of what your will says. 

If you have not updated your documents since remarrying, you may be leaving a primary wealth source to an ex-spouse—and leaving your current partner and children to fight for a diminished remaining share of your net worth.

Unintended Disinheritance

In many first marriages, a typical strategy is to leave everything to the surviving spouse. But in a blended family, this approach may be a recipe for an unintended disinheritance disaster.

Leaving everything to your new spouse with the verbal understanding that they will take care of your children from a previous marriage is risky. Once those assets transfer, your spouse has no legal obligation to honor that wish. They could remarry, have a falling out with your children, or leave everything to their own biological heirs, effectively cutting your children out of their inheritance.

Even with the best intentions, if your surviving spouse dies before updating their own estate plan, those assets may pass by law to their biological heirs, overriding what you may have both intended.

Asset Commingling

Newlyweds often move quickly to merge their finances, including bank accounts and property titles. However, once a separate asset, such as an inheritance or a home owned before the marriage, is commingled with marital funds, it can lose its protected status. 

Without a documented paper trail or a marital agreement, a family heirloom or the down payment for your child’s future home may be treated as marital property. If the marriage ends or you predecease your spouse, recovering those assets for the originally intended beneficiaries becomes extremely difficult, if not impossible. 

Incapacity Battles

Estate planning is not just about what happens at death. It is also about who speaks for you when you cannot speak for yourself. Medical care and end-of-life decisions are a frequent source of conflict between a new spouse and adult children from a prior relationship.

Without an updated healthcare power of attorney (POA) or advance directive, incapacity can trigger a dispute over decision-making authority between your legal next of kin and your biological next of kin. The result may be costly guardianship litigation, irreparable family rifts, and decisions made by a court rather than the people you actually trusted.

Strategic Solutions for Matching a Modern Family to a Modern Legacy

Couples can spend months or years planning their wedding and not dedicate a single moment to planning their estate. As family structures change, estate plans should change with them. Do not let yours sit in a drawer while your life moves forward—a blended family brings new opportunities and complications that your estate plan needs to reflect. 

Timely Beneficiary Updates

Updating your beneficiaries on retirement accounts and life insurance policies is the quickest win in estate planning, but for blended families, it requires more than simple name-swapping to ensure that these types of assets pass to the right people. 

  • Primary versus contingent. You may name your spouse as the primary beneficiary but designate your biological children as equal contingent (backup) beneficiaries.
  • Trust as beneficiary. Instead of naming a child directly—which could result in a 19-year-old receiving a massive lump sum—name your revocable living trust so you can control the timing and conditions of the payout.

Trusts to Balance Competing Goals

Trusts can also be an effective planning tool for resolving issues of perceived fairness in a blended family. Using a qualified terminable interest property (QTIP) trust, for example, lets you provide for your spouse without unintentionally disinheriting your children. You can place assets such as the family home into the trust, allowing your surviving spouse to live there or collect income for life. Upon their death, the trust’s terms legally mandate that the remaining assets pass to your biological children, preventing the assets from being redirected to the spouse’s own heirs or their potential future spouse.

Marital Agreements for Added Protection

A prenuptial or postnuptial agreement can take precedence over your will or state laws and give you more control over your assets. 

  • Waiving statutory rights. In most states, you cannot legally disinherit a spouse. They are entitled to an elective share (as much as 30–50 percent) of your estate. A marital agreement can legally waive these rights and allow you to leave a family business or a premarital home entirely to your children.
  • Defining “separate” property. These agreements serve as the definitive record of what you brought into the marriage, keeping your premarital wealth clearly distinct from marital assets.

Naming an Agent to Avoid Medical Showdowns 

To prevent the incapacity disputes mentioned earlier, your healthcare POA and advance directive must be clear and up to date. You do not want the hospital to guess who is in charge; explicitly name your spouse (or a child) as the primary agent.

If you anticipate tension between your new spouse and adult children, consider naming a neutral third party (such as a professional fiduciary or patient advocate) as a coagent who can help take personal feelings out of your sensitive (and stated) healthcare wishes. 

Planning for the “Day One” Remarriage Audit

The moment you sign the marriage license, your legal status changes in the eyes of the state, and the default state laws may not match your best intentions for how you want your estate passed on. 

Review your entire estate plan—including wills, trusts, beneficiary forms, and powers of attorney—immediately upon remarrying. 

There is also a limited window to finalize marital agreements. Without a marital agreement in place, your new spouse may be legally entitled to a share of your estate, no matter what your estate plan says. A prenuptial or postnuptial agreement is usually the only way a spouse can voluntarily waive these rights. 

Updating your estate plan now, while you are focused on building a shared future, can help protect your new marriage from becoming a legal battle for the next generation. 

Types of Life Insurance and How They Can Be Used in Estate Planning

Many people first encounter life insurance when they start a full-time job and are offered coverage through their employer’s group plan. It is an easy decision to make—and one that often receives little attention afterward. But as your financial and family circumstances evolve, your coverage is worth revisiting. 

What Is Life Insurance?

In general terms, life insurance is an agreement between you and an insurance company. You pay premiums over time and, in return, after you pass away, the company pays a lump sum of money (death benefit) to the people you choose (beneficiaries). This benefit is designed to help your loved ones cover expenses and replace the financial support you provide. 

When coordinated with your estate plan, the right type of life insurance can provide you with peace of mind and meaningful financial protection for your loved ones if you die unexpectedly. Because there are several types of life insurance available, it is important to understand the primary options and how they differ. 

Types of Life Insurance

  • Term life insurance. Term life insurance provides coverage for a specific period (term), such as 10, 20, or 30 years. If you die during the term, the policy pays a death benefit to your beneficiaries. If you outlive the term, the coverage ends, and no benefit is paid. Term life insurance is generally the most affordable type. It is often used to provide financial protection during key years, such as while you are raising a family or paying off a mortgage. 
  • Whole life insurance. Whole life insurance covers your entire lifetime, as long as you keep paying the premiums. Premiums are typically higher than term life insurance premiums but are usually designed to remain the same over time. Unlike term insurance, whole life insurance also builds cash value (money that grows inside the policy over the years). In many policies, you can access the cash value through a policy loan or a withdrawal. If you cancel (surrender) the policy, you may receive the remaining cash value after any fees and outstanding loans are deducted. 
  • Universal life insurance. Universal life (UL) insurance is a type of permanent life insurance that can last your entire life as long as the policy stays adequately funded. It includes a death benefit and a cash value account that can grow over time. A key feature of UL insurance is flexibility: within certain limits, you may be able to adjust your premium payments and, in some cases, the death benefit. The cash value typically grows based on an interest rate (or other crediting method) set by the insurer and may help cover the policy’s ongoing costs. If the cash value becomes too low or insufficient premiums are paid, the policy can lapse, leaving you without coverage. 
  • Variable life insurance. Variable life (VL) insurance is a form of permanent life insurance with a cash value that you invest in options offered by the insurer, typically funds similar to stock or bond mutual funds. Because the cash value is tied to investment performance, it can fluctuate, and poor performance can reduce the cash value and sometimes the death benefit. Some VL policies include a minimum death benefit, but it may depend on meeting certain requirements, such as paying sufficient premiums and limiting loans or withdrawals. Death benefits are generally income tax-exempt for beneficiaries, and cash value growth is typically tax-deferred while it remains in the policy. 
  • Variable universal life insurance. Variable universal life (VUL) insurance is a type of permanent life insurance that combines features of both variable and universal life insurance. Depending on the policy, it may offer
    • flexible premiums (within limits),
    • adjustable death benefits (within limits),
    • the ability to choose how the policy’s cash value is invested from options offered by the insurer,
    • the ability to borrow against the cash value, or 
    • the ability to make partial withdrawals.
  • Survivorship life insurance. Survivorship life insurance, sometimes called “second-to-die” life insurance, covers two individuals, most often a married couple. Instead of paying a benefit when the first person dies, the policy pays the death benefit only after both have passed away. These policies are often used in estate planning because the need for funds typically arises after both individuals are gone. For example, the death benefit can help cover estate taxes or other expenses, allowing heirs to keep assets, such as a family home, rather than having to sell them. Survivorship policies can be term, whole, universal, or variable, depending on your family’s goals.

Which Type of Insurance Is Best for Me?

With so many options available, choosing the right type of insurance can feel overwhelming. The best choice depends on your stage of life, financial situation, and long-term goals.

For example, a young couple just starting out may choose term insurance as an affordable way to provide financial protection, such as paying off a mortgage or replacing income if one spouse dies.  

A middle-aged professional with a family may consider a longer-term policy or permanent coverage, such as whole life insurance, to ensure a death benefit will be available even if future health changes make new coverage difficult to obtain.

For individuals with significant assets, such as a business or real estate, life insurance can provide liquidity to help fund a buyout or pay estate taxes. In these cases, policies that cover two people, such as survivorship insurance, may be appropriate.

Ultimately, life insurance is not one-size-fits-all. Working with your insurance professional, financial advisor, and estate planning attorney can help you identify your risks and select coverage that aligns with your overall plan. Insurance can be complex, but you do not have to navigate it alone. Reach out to our office today to discuss your options.

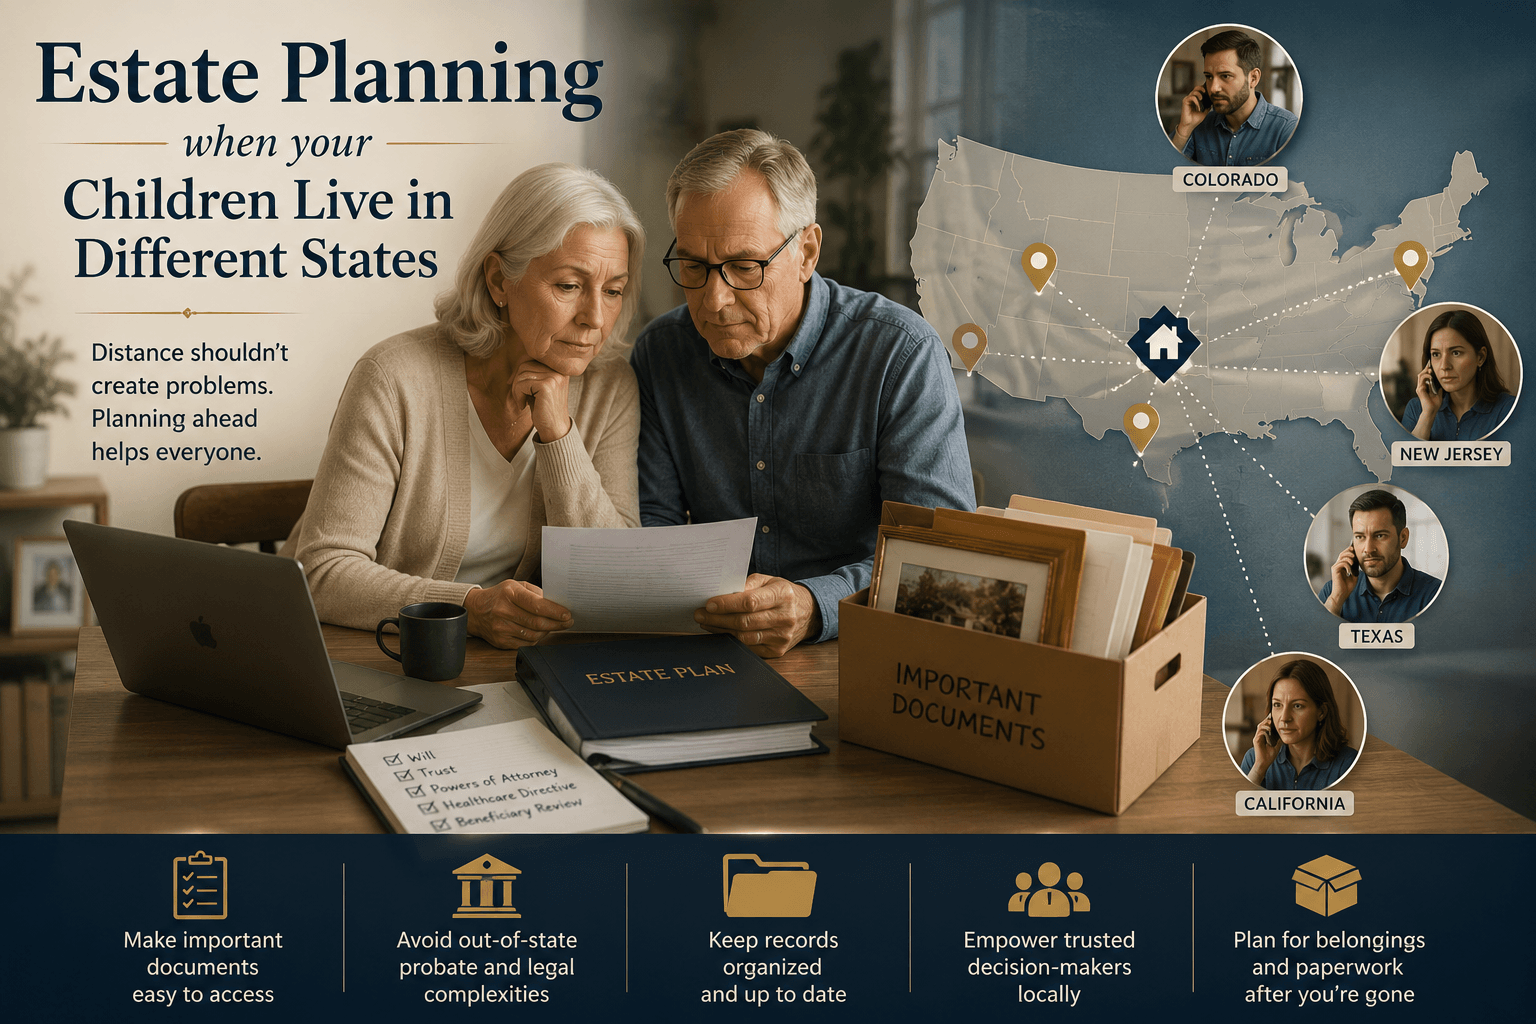
Estate Planning When Your Children Live in Different States

Today, many families are scattered across the country, with parents living in one state and children in another. 

Physical distance can introduce logistical hurdles that estate plans are not always built to handle. Even in a geographically clustered family, having a child living across state lines can create significant headaches if that child is named as a decision-maker.

There is no substitute for having a trusted loved one you can rely on when help is needed. But in a crisis, the “how” of your estate plan can become just as important as the “who.” It is not enough to name the right decision-makers. Your plan should also make it clear how quickly they can act, what authority they have, and how easily they can coordinate your care, manage your finances, or protect your household when time matters most. 

The Logistics of Trust 

Naming a child who lives far away as one of your trusted decision-makers may be a good choice on paper. In many instances, however, they should be close to you personally and physically when called upon to act. Even a short delay in carrying out your estate plan can have far-reaching consequences. 

Powers of Attorney

A power of attorney (POA) designates a trusted person (your agent) to make decisions on your behalf when you cannot, whether those decisions are financial or medical. Each type of POA requires its own separate document. Physical distance can affect financial and medical authority in very different ways. When deciding who your agents should be under your financial and medical POAs, consider the following:

  • Financial POA. Banking, paying bills, and managing assets are largely digital today. A child in Seattle can manage a parent’s finances in Florida with relative ease. If your most financially savvy child lives in a different state, they can still be an effective primary agent under a financial POA. However, ensure that the out-of-state agent is added to accounts or granted access to view accounts. Doing so allows for a seamless transition, enabling the agent to monitor for fraud or missed bills without having to physically visit a bank branch.
  • Medical POA. An agent under a medical POA often needs to be physically present to interface with doctors, oversee daily care, and manage the complex logistics of a hospital discharge or a transition to rehab. In this case, consider naming a primary agent paired with a local backup. You may name your most capable child (regardless of location) as the primary agent, but appoint a local successor or coagent who is authorized to act in immediate emergencies until the primary agent arrives. 

Executor

An executor is the person who settles your estate after you have passed away. Their role is often more hands-on than people expect and may involve securing and distributing real estate, sorting and valuing tangible personal property, and coordinating with local professionals such as attorneys, appraisers, and estate sale companies.

Naming an out-of-state executor can create logistical challenges. The executor may need to coordinate with local professionals, manage property from a distance, and handle court or filing requirements in another state. While related expenses are often reimbursable from the estate, they can still delay administration and increase costs. Some states also impose extra requirements on nonresident executors, adding paperwork and friction to the process. 

If the most qualified executor lives out of state, consider incorporating a local support mechanism, such as a local attorney, a licensed third-party administrator, or another trusted resource to handle on-the-ground logistics such as securing property and coordinating access. The named executor can remain the primary decision-maker while reducing travel, cost, and administrative friction.

The physical process of sorting through a parent’s belongings can be another demanding aspect of the executor’s role, especially from a distance. A local project manager or estate coordinator can provide crucial support by clearing a home, freeing up out-of-state children to focus on priority decisions.

Healthcare and Emergency Planning

Out-of-state children face a specific communication barrier during a health crisis: They cannot physically hand a document to a provider. Assuming they have the authority to act, they may encounter situations that require immediate action.

If a parent is hospitalized and key documents are not immediately available, a child living out of state may struggle to establish authority with providers. Hospitals may require copies of legal documents, not accept unfamiliar forms without review, and default to speaking with individuals who are physically present.

Once authority has been established, distance can still slow communication. Coordinating care decisions, speaking with multiple providers, and staying informed in real time are more difficult when the decision-maker is not on-site during a rapidly evolving situation.

Ensure that all decision-makers have immediate access to signed directives in a secure digital format, along with key provider contact information. Documents should be accessible on a smartphone or through a secure platform so they can be shared without delay.

Where appropriate, consider designating a local contact who can assist with in-person communication and coordination until the primary decision-maker arrives.

Property in Multiple States

Children may not be the only ones spread out among multiple states. Parents may have a vacation home, income-producing property, or other property located outside their home state, which can add yet another layer of logistical complexity to the estate. 

Real estate is governed by the laws of the state where it is located. When someone passes away, their estate typically goes through probate, a court-supervised process for settling debts and transferring assets to heirs. As a result, owning property in another state may require a separate probate proceeding—known as ancillary probate—in addition to the primary probate process in your home state.

An out-of-state executor may have to hire multiple attorneys, pay additional court fees, and manage parallel legal timelines across multiple jurisdictions. What may have been a single process becomes two or more, each with distinct rules, complexities, deadlines, and administrative demands.

Planning ahead can help reduce or avoid such complications. In some cases, structuring ownership through certain planning tools with the help of an estate planning attorney may allow assets to pass outside probate.

When no advance planning is in place, understanding where property is located and coordinating with professionals in those jurisdictions can still help streamline administration.

Practical Tips for Any Distance

The best-laid estate plan can fail if the practical connections are missing. The following high-level strategies can help bridge the gap between your plan and your family’s reality.

  • Keep a key contact list. An out-of-state child is unlikely to know who your trusted plumber is or which neighbor has a spare key. Write out a localized guide specific to your home, contacts, and routines. In a moment of urgency, this kind of practical knowledge can be just as valuable as legal authority.
  • Review your estate plan after a move. A child who is local today may be across the country next year. Revisit your choice of decision-makers whenever a family member moves. If your local backup relocates, your estate plan may no longer function as intended.
  • Initiate a digital “handshake.” In addition to naming primary agents and backups, connect them. If your out-of-state decision-makers and local supports do not already know one another, your plan may stall at the worst possible moment. A simple introduction in advance makes coordination easier for everyone.

Distance Does Not Have to Derail Your Plan

Many estate planning tasks can be performed remotely. But in time-sensitive situations, particularly medical emergencies, physical closeness can matter as much as, or more than, emotional closeness. Certain administrative and on-the-ground tasks are simply more efficient when handled by someone local. 

When your children live in different states, getting them on the same planning page requires a layered approach that bridges the distance and brings everyone together around shared goals.