What to Do with Grandma’s Ring: Dividing Personal Property in an Estate

If you have a beloved late grandmother, many images and memories may come to mind when you reminisce about her.

You might picture her at her home or at the family vacation house during the holidays. Your memory could be a special meal that only she prepared for you or a place she took you to. Or maybe you remember a piece of jewelry she always wore—one that several family members are eyeing as you go through the personal property in her estate. 

The little things in life can sometimes have sentimental value as well as financial value. For these reasons, personal items of the deceased can often create controversy when it is time to divide up belongings and there is no clear plan for who gets what.

Trash, Treasure, and Heirlooms

Discussions about who gets the car, the house, the silver, the stocks, and other big-ticket items take center stage in an estate plan: people often spend a great deal of time deciding how their largest assets will be divided among their loved ones. But small items can cause big disputes between family members, especially if more than one person wants the same thing and it is not specifically accounted for in an estate plan.

Jewelry is a perfect example of something physically small but potentially worth more emotionally and monetarily than any other property or account in someone’s possession. By the age of 50, many women own upwards of 150 pieces of jewelry. The likelihood of someone dying and leaving behind jewelry is therefore quite high. 

Yet while people usually remember the stories behind certain pieces, they may not know how much money their jewelry collection is actually worth. Take, for example, a British woman who got an appraisal of a diamond ring that she purchased for $13 decades earlier at the UK equivalent of a yard sale, assuming it was costume jewelry. She learned that it had an estimated value between $325,000 and $450,000. The ring later sold at auction for around $850,000.1 

Stories like these are more common than one might imagine. To prevent future conflict among loved ones, jewelry owners would be wise to inventory the value of key pieces in their jewelry collection and leave clear and legally binding instructions for how the collection is to be divided.

Residuary Clauses and the Residuary Estate

Items of personal property like heirlooms and jewelry, although individually small, can collectively make up a large part of a deceased person’s property. They may be treated as an afterthought and lumped together in a will or trust with their distribution being addressed through what is known as a residuary clause or a remainder clause.

A residuary clause might simply state that whatever property remains after specific gifts have been made (i.e., the residuary estate) should go to a single person or be divided among multiple people. 

This simple statement on paper, however, can turn into a complex situation when there are competing claims to the same item. 

Single Residuary Beneficiary

When just one person inherits the residuary estate, an executor, personal representative, or trustee should not encounter any significant distribution issues. That beneficiary receives Grandma’s ring and any other personal property that Grandma did not specifically gift to a particular individual. It is now their property, and they can do with it whatever they want. They can choose to wear the ring, reset it, sell it, or let it sit in their jewelry box. 

Multiple Residuary Beneficiaries

Issues arise when the residuary estate is left to multiple beneficiaries. Generally, the residuary estate is a pool of assets without a clear set of terms for how that pot is divided. Sometimes, the beneficiaries themselves are tasked with the job of dividing the personal effects among themselves; other times, the executor, personal representative, or trustee gets to decide.

Ideally, the beneficiaries can come to an agreement about who receives the ring and other property that does not have a designated beneficiary. Different items hold different meanings to different people. It is possible that each beneficiary has their heart set on a different item or set of items, and there is a neat division with no overlap and no quarrels. 

In cases where more than one family member is interested in the same item, the best-case scenario is that they can reach a peaceful resolution, perhaps involving trading other sought-after items. If there is an impasse, beneficiaries could sell the item in question and divide the proceeds equally. Another option is for one beneficiary to buy out the other beneficiary’s interest in the item. They could also draw straws or flip a coin. The solution may depend on whether the dispute is over a single item, like a ring, or over multiple items, resulting in a breakdown in the peaceful division of items.

Beneficiaries may look to the executor or personal representative of the estate or to the trustee of a family trust for answers. If clear instructions are not provided in the deceased person’s will or trust, the executor or trustee may have some discretion about how to carry out the decedent’s wishes. At the very least, they may be able to mediate to reach a solution. Executors or trustees who are also beneficiaries of the estate may have to proceed with extra caution to avoid conflicts of interest. 

As for who gets Grandma’s ring—or her pie plate, antique rocking chair, or anything else that belonged to her and does not have a named beneficiary—heirs, trustees, and executors need to brace for the possibility of an unresolved conflict that escalates to a legal dispute.

The Value of an Estate Plan

Sometimes, the best strategy for distributing personal possessions is to give things away while the owner is living. Asking loved ones what they want in advance can give everyone—including Grandma—a voice in the discussion about what to do with her belongings. This can provide more options for dividing possessions fairly and equally, either in person or through a will or trust. 

A thorough estate plan also goes a long way toward avoiding family fights over heirlooms and keepsakes. Without proper estate planning, the odds of a family conflict increase. 

Our attorneys are here for all of your planning and post-planning needs. In addition to helping people plan for how they want their personal possessions to be distributed after their death, we can assist executors and trustees in the administration process of distributing these items from an estate. Schedule a meeting to learn more.

  1. Zahra Jamshed, Diamond Ring Purchased for $13 as Costume Jewelry Sells for $848K, CNN (June 8, 2017), https://www.cnn.com/style/article/car-boot-sale-diamond-ring-sells-for-847k/index.html↩︎

Will My Revocable Living Trust Avoid Probate? It Depends.

If you have established a revocable living trust (which we will refer to simply as a trust), congratulations! You are on the right track in creating a comprehensive estate plan. However, you are only halfway there. Many people believe that because they took the time to create a trust, their estate will automatically avoid probate, and they will not have to take any additional steps. Unfortunately, this assumption creates a false sense of security.

The key to probate avoidance is ensuring that, when you pass away, there are no accounts or property in your sole name without a current beneficiary designation. Taking this one step further, ensuring that the provisions of the trust you created will govern the management and ultimate distribution of your accounts and property after you pass away requires that you have either properly transferred ownership of your accounts and property to your trust or named your trust as the beneficiary.

What kinds of things go through probate?
Under what conditions will your loved ones have to go to probate court to administer and distribute your accounts and property after your death? Here are a few examples:

  • Your accounts and real estate are titled in your sole, individual name (without a payable-on-death (POD) or transfer-on-death (TOD) designation)
  • You own accounts and real estate jointly with someone else as a tenant in common
  • Your retirement accounts have no named beneficiary 
  • Your life insurance policies have no named beneficiary

How can you ensure that your accounts and property avoid the probate process?
The following types of accounts and property will automatically avoid probate after you die and, therefore, do not need to be funded into your trust; however, you can choose to have some types funded into your trust at death:

  • Accounts and real estate owned as joint tenants with rights of survivorship. Your interest in the accounts and real estate will transfer to the surviving owner automatically at your death by operation of law.
  • Accounts and real estate owned by a married couple as tenants by the entirety. Your interest in the accounts and real estate will transfer to the surviving spouse automatically at the time of your death by operation of law, leaving them the sole owner of the property. 
  • Life insurance, if you have designated a beneficiary on the policy. In many instances, you may choose to name your trust, if you have created one, as the beneficiary of your life insurance policy. Naming your trust as the beneficiary will cause the life insurance proceeds to flow into the trust at your death.
  • Retirement accounts, 401(k)s, and annuities. If you have designated a beneficiary on the account or the plan has default rules requiring that the account be distributed to a specific person or group of people if there is no named beneficiary, the account will go to that person or people. You might also consider naming your trust as the beneficiary of the retirement account so that the account will flow into your trust at the time of your death.
  • POD and TOD accounts and, in some states, TOD or beneficiary deeds for real estate. Accounts or real estate with these types of designations will automatically transfer to the named beneficiary upon your death by operation of law.

What happens if you forget to fund your trust?

Life is ever-changing, and you could overlook an account or property when funding your trust. Or you could take all of the steps necessary to ensure that all of your current assets are in the trust at the time of your death but then acquire new accounts or property and forget to fund the new items into your trust. If one of these situations arises, your loved ones may have to open a probate process at your death to handle any accounts or property that were in your sole name without a beneficiary designation. 

Ideally, when you created your trust, you also created a pour-over will, which instructs the judge in a probate administration to transfer all of the accounts and property in probate to your trust during the probate process. So, even if your loved ones end up having to go through probate, the accounts or property will eventually end up funded into your trust and managed according to the trust instructions. While this situation is not ideal and in many states may be very expensive and time-consuming, the ultimate outcome is that your trust remains the sole vehicle for managing and distributing all of your accounts and property.

What is the next step?

Ask a qualified estate planning attorney to confirm that your trust is fully funded and that all your accounts and property are aligned with your estate plan. Remember, creating a revocable living trust is just the first step to probate avoidance, and proper ownership is the ultimate key.  

How to Choose a Conservator for Yourself

Every day we make hundreds of decisions for ourselves—from what to eat for breakfast to where to vacation. However, what happens if you cannot make decisions for yourself? Who do you want making day-to-day decisions on your behalf and serving as your conservator?

If you have recently created or reviewed your estate plan, you probably discussed and signed a financial power of attorney. For those of you on the fence about completing your estate plan, this important tool allows you to authorize an individual of your choice to manage your financial affairs (for example, sign checks in your name, open a bank account, manage your real property, enter into contracts on your behalf, etc.). This can be very beneficial if you are no longer able to do these things for yourself; someone else can legally step in and handle these tasks for you immediately. 

However, you may run into situations in which third parties will require the nominated individual to have explicit authority to complete tasks or manage your financial affairs in a way that is not provided through a signed financial power of attorney. In these cases, if you no longer have capacity, your loved ones may need to go before a judge and have them appoint a conservator for your benefit. This is why you should not only appoint an agent in your financial power of attorney but also nominate a conservator for yourself in case the need for one arises (if permitted in your state). This can often be accomplished through documents such as a declaration of preneed guardian (the title of this tool may vary depending on your state of residence). 

A conservator is essentially a court-appointed and court-controlled agent. Depending on your state law, this person may also be referred to as a guardian or guardian of the estate. The person in this role is granted and delegated authority through the court to handle your financial affairs on your behalf if you cannot do so on your own. In many jurisdictions, if a guardianship or conservatorship is required, the court will give priority to an individual who has been named as an agent or desired conservator under a financial power of attorney, making it incredibly important that you have one prepared. 

If you do not have one of these tools in place, each state has a law that defines the order of priority in which people are appointed to serve in this role. In some cases, you could end up having someone handling your affairs whom you would have never wanted, like an estranged parent or sibling. A financial power of attorney allows you to share your wishes and preferences with the court.

To ensure that you are taken care of by someone you trust when you can no longer take care of yourself in the way you desire, it is important that you choose the right person. When analyzing the pool of candidates, consider the following questions:

  • Do they have the time to act as your guardian? Often, the most organized and knowledgeable individuals are also the most heavily scheduled and may not be able to step in easily.
  • Do they live close by? Even in our digital world, some issues may take multiple steps or require in-person interactions to resolve. If the individual you are considering appointing lives far away, they may not be able to carry out their duties fully without unnecessary time and expense.
  • Do they have the necessary skill set? When acting as a conservator, it is crucial that the individual you select is organized, thorough, and able to communicate clearly. A person who is scattered or is unreliable is unlikely to be a good advocate for you.

While we all want to retain as much autonomy as possible, there may come a time when we need someone to act on our behalf. Selecting the right individual to act as your advocate and ensure that you are taken care of according to your wishes is especially important. If you have any questions or would like to discuss whom you should appoint for this role, contact us. We are here to help.

Who Should Be Your Successor Trustee?

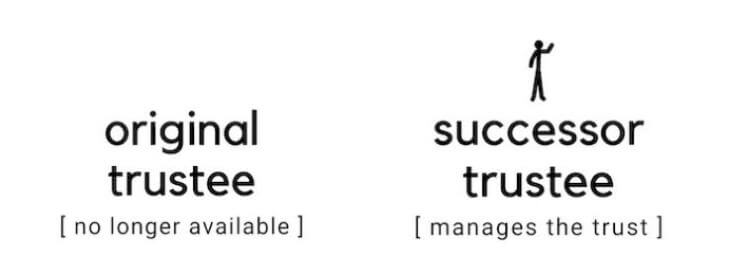
If you have a revocable living trust, you probably named yourself as the initial trustee so that you can continue to manage your financial affairs. However, someone else will eventually need to step in to administer your trust when you are no longer able to act due to incapacity (the inability to manage your affairs) or after your death. This person is known as your successor trustee.

Key Takeaways

  • Because successor trustees hold great responsibility, you should choose them carefully.
  • Successor trustees can be an adult child,a family member, atrusted friend, a corporate or professional trustee, or a financial institution.

Responsibilities of a Successor Trustee

At incapacity. If you become incapacitated during your lifetime, your successor trustee will take full control over the administration of your trust for you, making financial decisions, selling or refinancing property, and completing other tasks related to your trust’s accounts and property. Your successor may also be involved in paying bills and ensuring you get any care you need. Since your successor trustee can only manage accounts and property that the trust owns, it is important that you fully fund your trust (in other words, transfer or retitle your accounts and property to your trust). When you are no longer serving as the trustee of your revocable living trust, it does not mean you will no longer benefit from the assets held within your trust. You will remain a beneficiary of the trust until you pass away.

After death. After you die, your successor trustee will act similarly to an executor of a probate estate. The successor trustee will inventory the trust’s accounts and property, pay your final bills, sell trust property if necessary, have your final tax returns prepared and filed, and distribute the trust’s accounts and property according to the trust’s instructions. As in the case of your incapacity, the successor trustee is limited to managing accounts and property owned by the trust, so fully funding your trust is crucial. 

Your successor trustee will typically act without court supervision, which allows your affairs to be handled privately and efficiently. This is probably one of the reasons you established a living trust in the first place. However, this also means it will be up to your successor trustee to initiate the administration of your trust and keep the process moving fairly so that no one brings an action in court that will cause court supervision. 

An Important Consideration 

Your successor trustee’s ability to control and manage the trust’s accounts and property is dictated by the trust’s instructions. In carrying out their duties and making investment and management decisions, the successor trustee must act carefully to avoid breaching their fiduciary duties. Fiduciary duties are a set of rules under state law that ensure any action taken by a fiduciary (here, the successor trustee) is in the best interest of the trust beneficiaries and complies with the law.

Who Can Be a Successor Trustee

A successor trustee can be an adult child, a family member, a trusted friend, or a professional or corporate trustee (for example, a bank trust department or trust company). You should name multiple backups in case your first choice is unable or unwilling to act.

The successor trustee does not need to know exactly what to do and when because they can seek counsel from an attorney, certified public accountant, or other advisor to assist them in their responsibilities. Nevertheless, you must name someone responsible, conscientious, and willing to seek professional guidance when warranted.

What You Need to Know  

Your successor trustee should be someone you know and trust, whose judgment you respect, and who will also respect your wishes.

When choosing a successor, keep in mind the type and number of accounts and property in your trust and the complexity of the provisions within your trust document. For example, if you plan to hold accounts and property in a continuing trust for your beneficiaries following your death, your successor trustee will have more responsibilities for a longer period than if your accounts and property were given to your beneficiaries immediately upon your death.

  • Consider your candidates’ qualifications, including personalities, financial or business experience, and availability due to family or career demands. Being a successor trustee can take a substantial amount of time and requires a certain business sense.
  • Discuss this nomination with the people you are considering to ensure they would be willing to take on this responsibility. Do not assume they would accept this role without having been educated on what is involved.
  • Trustees should be paid for their work; your trust document should provide fair and reasonable compensation for successor trustees. If you nominate a professional or corporate trustee, they will have their established rate for trust work.

Rest assured, we can help you select, educate, and advise your successor trustees. You are not alone in making this important decision. If you have any questions or concerns, please schedule an appointment with us.

How to Choose the Initial Trustee of Your Trust

When you establish a trust, you nominate someone to be the trustee. If you are creating a revocable living trust, you will likely be the initial trustee. You will also want to name successors or backup trustees to step in and manage the trust’s affairs if you can no longer manage the trust yourself. The trustee is in charge of managing the trust’s accounts and property. Specific duties can include collecting income, paying bills and taxes, making investment decisions, buying and selling property, providing money for you (during your lifetime) and your loved ones according to the trust’s instructions, keeping accurate records, and generally keeping things organized and in good order.

Key Takeaways

  • You can be the trustee of your revocable living trust. If you are married, your spouse can be your co-trustee.
  • Most irrevocable trusts do not allow you to be a trustee.
  • Even though you can be the trustee, you may not always be the best choice.
  • You can choose an adult child, a trusted friend, or a professional or corporate trustee to act as trustee.
  • As a trustee, you can hire certain individuals or professionals to assist you or any successor trustee in managing your trust. 
  • Naming someone else to be a co-trustee with you helps your co-trustee become familiar with your trust, allows your co-trustee to learn firsthand how you want the trust to operate, and lets you evaluate your co-trustee’s abilities. As a practical tip, if you decide to add a co-trustee, you may want to talk to your banks and other financial institutions to learn their co-trustee policy. Some do not like to work with co-trustees in general, while others require that the terms of the trust state that each co-trustee can act independently of each other (rather than requiring both co-trustee’s signatures or authorization for all acts on behalf of the trust).  

Who Can Be Your Initial Trustee

As previously mentioned, you can be your own trustee if you have a revocable living trust. If you are married, your spouse can be a co-trustee. If either of you cannot manage your affairs or dies, the other can usually continue to handle your financial affairs without interruption. Most married couples who own accounts and property together, especially those who have been married for some time, usually elect to serve as co-trustees.

However, you do not have to be your trustee. Some people choose an adult child, trusted friend, or relative to serve in this capacity. Some individuals prefer a professional or corporate trustee (e.g., a bank trust department or trust company) due to their experience and investment skills. Nominating someone else to serve as trustee or co-trustee of your trust does not mean you lose control. The trustee you nominate must follow the instructions within your trust and may ultimately report to you. In many cases, you can even replace your trustee if you change your mind or the arrangement is not working out how you had imagined.

When to Consider a Professional or Corporate Trustee

A professional or corporate trustee is valuable in several instances. You may feel as though you are not able to serve as trustee for a variety of reasons. If you are elderly, widowed, or in declining health with no children or other trusted relatives living nearby, and your other potential candidates may lack the time or ability to manage your trust, a professional trustee may give you peace of mind that your affairs are being handled appropriately. Or, you may simply not have the time, desire, or experience to manage investments by yourself at any age or health status. Also, certain irrevocable trusts may not allow you to act as a trustee due to tax law restrictions. In these situations, a professional or corporate trustee may be exactly what you need: they have the experience, time, and resources to manage your trust properly and help you meet your investment goals.

What You Need to Know

Professional or corporate trustees will charge a fee to manage your trust. Usually, the fee will be based on the value of the trust’s accounts and property they will manage. Although these fees can be high, you may consider them worthwhile, especially considering their experience, the quality of the services provided, and the investment returns a professional trustee can deliver.

Actions to Consider

  • Honestly evaluate whether you are the best choice to be your own trustee. Someone else may do a better job than you, especially with regard to investing your money. However, if you choose to be the trustee of your own trust, you can still hire financial advisors to assist you in making the right investment choices. You do not have to do everything yourself.
  • Depending on your situation, it may be a good idea to nominate someone to serve as co-trustee with you now. This eliminates the time a successor would need to become knowledgeable about your trust, your accounts and property, and your beneficiaries’ needs and personalities. It would also allow you to evaluate whether the co-trustee is the right choice to manage the trust in your absence.
  • Evaluate your trustee candidates carefully and realistically. Some may assume that their oldest adult child would make a good trustee. Unfortunately, birth order may not accurately indicate financial management skills.
  • If you are considering a professional or corporate trustee, talk to several and compare their services, investment returns, and fees.

We can help you select, educate, and advise your successor trustees so they will have support and know what to do next to fulfill your wishes. Give us a call today. 

How to Pick a Trustee, Executor, and Agent under a Power of Attorney

While the term fiduciary is a legal term with a rich history, it generally means someone who is legally obligated to act in another person’s best interest. Trustees, executors, and agents are examples of fiduciaries. When you select people to fill these roles in your estate plan, you are picking one or more people to make decisions in the best interests of you and your beneficiaries and in accordance with the instructions you leave. You should also choose multiple backups for each of these roles in case your first choice is unable or unwilling to act when the time comes.

Understanding the basics of what each role entails and what to consider when making your choices can help ensure that your estate plan is effective. 

Trustee

A revocable living trust is often the center of a well-designed estate plan because it is the best strategy for achieving most people’s goals. You (as the trustmaker) will usually serve as the initial trustee and continue to manage the trust’s accounts and property in the same manner that you did before the trust was created. You will appoint a successor (backup) trustee in the trust agreement to be responsible for ensuring that your wealth is managed in accordance with your wishes after your death or during your incapacity (when you can no longer manage your affairs). It is best to have a trusted person or financial institution carry out this vitally important role. 

Your successor trustee will control only the accounts and property owned by the trust. If you own accounts and property in your sole name—that is, not as the trustee of your trust—your successor trustee will not be able to manage those items upon your death or incapacity. You will have to rely on your financial power of attorney to give someone the authority to manage those accounts and property while you are incapacitated. 

When you pass away, accounts and property in your sole name without a beneficiary designation may have to go through the probate process. Probate requires your executor to step in and manage those items and ultimately distribute them to the people who have priority under state law (who may not be the people you would have chosen). This is why it is of the utmost importance to appoint the right person to be your successor trustee and to fund your living trust fully.

Powers of Attorney

Powers of attorney are the documents in your estate plan that appoint individuals to make decisions on your behalf if you are alive but unable to do so yourself. There are a few different types of powers of attorney, each with their own specific areas of responsibility. We can help you decide which types of powers of attorney you will need based on your current situation and future goals. Here are two common types to include in your estate plan:

  • Financial Powers of Attorney 

Financial powers of attorney grant the fiduciary you select the ability to take financial actions on your behalf, such as purchasing life insurance or withdrawing money from your bank accounts to cover your expenses. A fiduciary who acts under the authority given in a financial power of attorney is generally called an agent. Your agent is only able to manage the accounts and property that are not owned by your trust. If an account or property is owned by the trust, it is the responsibility of the trustee to manage that item, as discussed above. You can name an individual as your agent or, in some circumstances, you can name an institution, like a trust company. While in most states your agent is permitted to charge a fee for acting as your agent under a financial power of attorney, keep in mind that trust companies generally charge higher fees and will likely not waive fees like your loved ones might.

  • Healthcare Powers of Attorney and Related Documents

A healthcare power of attorney allows you to name a trusted person to make or communicate your medical decisions on your behalf when you cannot do so yourself. These decisions may range from deciding what surgeon to use to whether to remove you from life support. Other documents can be used in conjunction with the healthcare power of attorney to cover specific actions that can be taken regarding your medical needs, such as making decisions about the types of care you wish to receive or who can access your medical information.

Executor

Your executor (called a personal representative in some states) is the person who will see your accounts and property through probate, if necessary, and carry out your wishes based on your last will and testament if you have one. Depending on your preferences, your executor may be the same person or institution as your successor trustee. 

Some individuals choose to name a professional as their executor. The professional is usually someone who does not stand to gain anything from the will and can be a good choice if you own a great deal of different property and accounts to be divided among many beneficiaries. In other words, the more complex your estate and distribution scheme, the more it may make sense to have a professional in charge. A professional may also make sense if you do not have someone you personally know who can serve as the executor. Family or friends may serve, but it is important to consider the amount of work involved before placing this burden on someone who has little time or experience administering the estate of someone after they pass away.

Being an executor can be hard work and may have court-dictated deadlines; it is crucial to pick someone you know will be up to the job. They will probably need to hire an accountant to help sort out your taxes and a lawyer to assist in the process. If there is a dispute, then attorneys, appraisers, mediators, or other professionals will undoubtedly need to be involved. Choosing a spouse or another loved one to serve as your executor may be convenient because they may already be familiar with what you own and have an easier time ensuring that your wishes are carried out. However, because of the time involved and the nature of some accounts and property, they may not be up to the task at the time. 

Get in Touch with Us Today

Let us help you make the process of picking your trustee, agents under powers of attorney, and executor as smooth and headache-free as possible. Once you have these choices in place, you will be able to rest easy knowing that your estate plan is in good hands no matter what life brings. Call us to make an appointment today.

Should Your Child’s Guardian and Trustee Be the Same Person?

If you have overheard any estate planning discussions, you have likely heard the words “guardian” or “trustee.” In estate planning, deciding who will ultimately be tasked with caring for your minor child or managing funds for their benefit is an important decision that requires consideration of many factors. 

Although there is no substitute for you as a parent, a guardian is someone who steps in when you pass away to assume your parental role and raise your minor child through legal adulthood. Conversely, a trustee manages the financial legacy you leave behind for your minor child. As a parent, you need to consider the skills and characteristics each role requires to ensure that you nominate the right people for the benefit of your child and their inheritance.

Who Makes a Good Guardian?

When choosing a guardian, the top consideration is who will love and raise your child like you would. Keep in mind the potential guardian’s religious beliefs, parenting style, interest in extracurricular activities, energy level, and whether they have children. You may want to consider where the individual lives and whether they have the capacity to provide daily love, care, and support for your child.

Who Makes a Good Trustee?

While the guardian you choose may be great at caring for your children, they may not be great at managing money. For this reason, it may make sense to place the financial management of your child’s funds in someone else’s hands. The person responsible for managing your child’s inheritance is the successor trustee or trustee. Not surprisingly, when choosing a trustee, the most important characteristic is that they manage finances well. However, they often do not need specialized knowledge or training. This individual can seek assistance from financial professionals should the need arise. The trustee must be able to manage the funds in accordance with your intent and pursuant to the trust’s instructions. 

Consider whether your potential trustee will agree and comply with the way you have structured the payout plan for your child’s inheritance (for example, giving your child a portion of their inheritance at different ages). If they do not agree with your wishes, it may be difficult for them to enforce them. Likewise, if you want to give your successor trustee discretion in managing funds and distributing inheritances rather than setting forth ages at which distributions are to be made, you should ensure that your trustee will use their discretion in alignment with your intent. In short, you want to choose a trustee to manage your child’s inheritance who will act in your minor child’s best interest within the limits you have set forth in your estate plan documents. 

Should They Be Different People or the Same?

Whether you select the same person to act as guardian for your minor child and successor trustee for your child’s inheritance will likely be based on the ability and capacity of the specific person. Some people may have the skills required to manage both roles effectively, which can simplify certain aspects of the process because the guardian will not have to go to someone else to request distributions to care for your minor child. 

On the other hand, not every person can do both jobs. With two different people serving in these roles, you can ensure that you have the right person for each job if one person is not ideal for both. Also, some individuals choose to designate a guardian from one spouse’s family and a trustee from the other spouse’s family to establish a system of checks and balances. This approach ensures that both sides of the child’s family are equally involved and each individual remains accountable. If you choose two different people for the roles of guardian and trustee, consider how the two get along, as they will likely have to work together and coordinate frequently while your child is under the age of majority.

Seek Help to Make Your Decision

While the estate planning process can be daunting, it does not have to be. Contact a knowledgeable estate planning attorney to help guide you through this process. We can explain your options and help you determine the best plan that will follow your wishes while meeting your family’s needs.

Do It Now: Name a Guardian for Your Minor Children

We know it is difficult, even horrific, to imagine someone else raising your children. However, you must consider who you would choose to fill this important role. Otherwise, a judge—a stranger who does not know you or your wishes, your child, or your relatives and friends—will determine who raises your children if something happens to you. Depending on state law, your children’s guardian could be a relative you do not get along with or, less commonly, a stranger you have never met. 

No one will ever be you or parent exactly like you. More than likely, however, someone you know could do a decent job providing for your children’s general welfare, education, and medical needs if you can no longer do so. Parents with minor children must name someone to raise their children in the event both parents die or are otherwise unable to care for them before the children become adults. While the likelihood of you and the children’s other parent both passing away or becoming unable to parent your children is slim, the consequences of not naming a guardian can be severe and are well worth contemplating and addressing.

If no guardian is nominated within your will or separate writing, if recognized and allowable in your state, a judge will decide who raises your child. Anyone can ask to be considered, and the judge will select the person they deem most appropriate. Families tend to fight over the custody of children when a loved one dies, especially if money is involved. On the other hand, if you name a guardian, the judge will likely support your choice as long as the individual you select is willing and able to take on the responsibility of raising your children.

How to Choose a Guardian

Your children’s guardian can be any individual you feel comfortable with, whether they are a relative or friend. Here are the factors our clients have considered when selecting guardians (and backup guardians). 

  • How well the children and potential guardian know one another and whether they enjoy spending time together
  • Parenting style, moral values, educational level, health practices, and religious or spiritual beliefs 
  • Where the guardian lives; if it is far away, your children would have to move from a familiar school, friends, and neighborhood to a new and unfamiliar location
  • The age and health of the guardian-candidates:
    • Grandparents may have the time but not the energy to keep up with a toddler or teenager. 
    • An older guardian may become ill or pass away before a child is grown, so your child could potentially face the loss of an additional parental figure.
    • A younger guardian, especially a sibling, may be too focused on establishing their own lives, especially if they are finishing college or starting a career.

WARNING: Serving as guardian and raising your children is a big deal; do not spring this responsibility on anyone without speaking with them about your expectations and ensuring they are willing and prepared. Ask your top candidates if they would be willing to serve, and ensure you name at least two alternates if your first choice cannot serve.

Who Is in Charge of the Money?

Raising your children should not be a financial burden for the guardian, and a candidate’s lack of finances should not be the deciding factor. Ideally, you can provide enough money (from your accounts, property, and life insurance) to provide for your children after you pass away. Some parents also earmark funds to help the guardian buy a larger car or house or build an addition onto their existing home so there is plenty of room for taking on the responsibility and addressing the needs of extra children.

Additional Factors to Consider When Deciding Who Manages the Children’s Money

  • In some circumstances, naming a person separate from the guardian to manage your children’s inheritance may be a good idea. That person would fill the role of your successor trustee and manage the money and property set aside for the children in a trust designed for them. The guardian would be responsible for the day-to-day raising of the children.
  • Under appropriate circumstances, having the same person raise the children and handle the money can simplify things because the guardian would not have to ask someone else to make distributions for the children’s benefit.
  • In some situations, the best person to raise the children may not be the best person to handle the money, and it may be tempting for them to use this money for their own purposes. So, dividing the responsibilities may be particularly beneficial and avoid the misuse of any money you leave for your children’s benefit.

Let’s Continue This Conversation

We know thinking about death or your potential inability to care for your child is not easy, but do not let that stop you from creating a proactive plan to address the unexpected. We are happy to talk this difficult topic through with you and legally document your wishes so that they are enforceable at your death. Understand that you are not bound to your initial selection and can change your mind and select a different guardian at any time. The chances of actually needing the guardian to step in are usually slim (we always hope this is the one nomination that is never needed). However, your job as a parent is to provide for and protect your children, so begin planning by calling our office for an appointment.

Things to Consider When a Parent Is Out of Town

Your estate plan may include powers of attorney that allow a trusted person to act on your behalf and advocate for you with regard to medical and financial matters when you cannot do so yourself. But do you have a similar document in place that gives someone the authority to care for your minor children when you are not able to? 

A comprehensive estate plan covers contingencies not only for you but also for your minor children. A delegation of parental authority (DOPA), often called a power of attorney (POA) for parents or parental POA, allows you to give a nonparent the legal authority to make certain decisions for your minor child. 

Delegating your parental authority to another person in a legal document can help ensure that your child receives the care they need when you are out of town on business or vacation. The document typically does not require a court order and does not supersede your parental rights. 

Why Use a DOPA or Parental POA?

Up until a certain age, your kids rely on you for almost everything. You might not realize just how much they depend on you until you are not there for them. 

Even when you leave the kids with a babysitter for a short period, it can quickly become apparent from the long list of instructions you provide just how many important tasks and details a parent is responsible for daily. 

As kids grow older and become more independent, they often require less from you. However, until your child reaches age 18, you are legally responsible for their well-being, and there are some things—such as receiving medical treatment or entering into a contract—for which a minor child must obtain parental permission. 

A DOPA or parental POA is a document that temporarily allows someone else—known as an agent or attorney-in-fact—to care for your child and act on their behalf similarly to the way you could. This tool is commonly used when a parent is leaving the state or country for a personal or work trip or when a parent is facing incarceration, military deployment, long-term medical treatment, or risk of deportation. 

This document does not override or interfere with your parental rights regarding the care, custody, and control of your child, but it does permit a caregiver to act in your stead on important matters like taking them to the doctor, excusing them from school, attending and consenting to school activities, inspecting and obtaining their records, and making decisions during an emergency. 

Not having a DOPA or parental POA for your minor child could mean that crucial care cannot be provided in a timely way—or at all—in your absence. It could also mean that in an emergency, the school or some other authority could make a choice based on their policies and procedures about your child’s care that you may not agree with. 

How a DOPA Works

The legal form you use to give quasi-parental rights to a third party may go by different names in different states. 

Minnesota and Idaho, for example, use the term delegation of parental authority. Washington refers to it as a power of attorney for parents. Oregon calls it a power of attorney over a child. North Dakota calls it a power of attorney for care and custody of minor child. And Florida refers to it as a designation of healthcare surrogate for minors.

State law can also vary on the specifics of how the document works. Some states limit a DOPA to a maximum of six months from the date it is signed, after which time a new agreement must be signed. In other states, a DOPA is good for up to one or two years. 

States may have different requirements for completing and validating the document. State law might require a DOPA to be notarized before it takes effect, and there may be a requirement to inform the other parent about the agreement, with limited exceptions. If the person who is going to care for your child lives in a different state, you may need to fill out a DOPA form in that state as well. 

Despite these differences, DOPAs work similarly in most states and share the following traits: 

  • A separate DOPA needs to be filled out for each minor child. 
  • A parent can withdraw a DOPA at any time. 
  • The person named as attorney-in-fact can be any adult. They do not have to be a family member or US citizen. 
  • The DOPA does not take away your right to make decisions for your child. You can still overrule a decision made by the attorney-in-fact. 
  • DOPAs are not transferable. 

DOPA forms typically state that the attorney-in-fact has all of the power and authority that the parent or guardian has (except the power to consent to marriage or adoption). They also provide the option for a parent to delegate to the attorney-in-fact only specific powers and responsibilities that are listed in the document. 

Other Considerations for a Parental Power of Attorney

The person you choose to make decisions for your child should be someone you know well and trust. But it may be worth asking if they would make the same choices you would make in the types of situations that could come up. 

You cannot expect your attorney-in-fact to be completely aligned with you on every conceivable scenario. While they will probably be able to check with you about a nonemergency decision, they will still need a degree of autonomy to act independently and exercise their best judgment if something unexpected happens and you cannot be reached right away. 

Choosing a close friend, family member, neighbor, or another responsible adult with whom you share similar values can help ensure that you are in accord about most important issues. 

The person you choose should be somebody your child is familiar with and comfortable around so that your child is receptive to their care and authority. Discuss the appointment of the short-term caregiver with your child and talk about your upcoming trip with them. 

Extended time away from a parent can be difficult for a child. Establishing expectations and a schedule of how often you will check in—both with your child and the caretaker—can keep everyone on the same page and ease the apprehension surrounding your absence. You know your kid best, though, and frequent check-ins might make them more anxious. 

In addition to emotional considerations, there are some practical points to keep in mind as you get ready to embark on your trip: 

  • Schools, doctors, banks, and other individuals and organizations should recognize and accept the power of attorney. However, double-check to make sure that this is the case before leaving. Your child’s doctor or school may have their own forms that are needed to access records, pick them up from school, or authorize care for them. 
  • Make copies of the DOPA so that the attorney-in-fact can give them to authorities who might need proof that they are in charge of the child. Keep at least one copy for yourself. 
  • Estimate ahead of time how much it will cost to care for your child while you are away and ensure that there are adequate funds to pay for their needs. You may want to give the caregiver money or leave them a credit card. 

The attorney-in-fact should also have the following information about your child: 

  • School name and phone number 
  • Teacher’s name
  • Medical insurance information 
  • Names and phone numbers of healthcare providers
  • Allergies (food, medicines, and environmental) 
  • Daily routines and activity schedules 
  • Contact information for friends and friends’ parents

Your profession, travel destination, and the type of trip you are taking could potentially put you at risk. The US government encourages travelers to high-risk areas to enroll in the State Department’s Smart Traveler Enrollment Program, develop a communication plan with loved ones, and discuss a plan with them about care and custody of children. 

Add an Up-to-Date Estate Plan to Your Travel Checklist

Traveling out of town when you have children can be stressful for them and for you. There is no substitute for a parent’s love and care. But if work or other circumstances keep you away from your children, a DOPA or parental POA might be the next best thing. 

A comprehensive estate plan should also cover a permanent guardianship arrangement for your children on the off chance that a worst-case scenario unfolds while you are away. 

Part of estate planning is thinking about what could happen to you and putting measures in place to protect your family. Your current estate plan may not address childcare and guardianship issues, or you might need to make updates to your plan to reflect current circumstances, such as the birth or adoption of a child, divorce, or nominating a new guardian in your will. 

You cannot protect your children from everything. But you can leave as little to chance as possible with a well-thought-out estate plan. To create or update your plan, schedule a meeting with an estate planning attorney.

Won’t My Spouse and Kids Inherit Everything When I Die?

You may think that if you die while you are married, everything you own will automatically go to your spouse and children. But you are actually thinking of state rules that apply if someone dies without leaving a will. In legal jargon, this is referred to as dying intestate. In that case, the specifics will vary depending on your state’s law, but generally, your spouse will receive a share of what you own, and the rest may be divided among your children or parents, depending on your situation. Exactly how much your spouse will inherit depends on the state law, though.  

Now, it may seem like so far, so good. Your spouse is getting an inheritance, and so are the kids. But here are some examples of how the laws can fail in many common family situations.

First, when it comes to who will get your money and property, most states’ laws presume that a family comprises a married couple and their biological children. But because that is not how many families are structured, things can quickly become legally complicated.

One analysis identified 50 different types of family structures in American households.1 Approximately 40 percent of all marriages in the United States are remarriages for at least one spouse,2 and—through adoption and stepfamilies—millions of children are living in blended families. Unfortunately, the laws have not kept up, and absurd results can occur if you rely on intestacy as your estate plan. Stepchildren whom you helped raise (but did not legally adopt) may end up with no inheritance, while a soon-to-be-ex-spouse may inherit from you.

For example, Carey and Blake each have a child from a prior relationship (Carey has a daughter, Rose; Blake has a son, Whitley) living with them full time. During the course of the marriage, Carey and Blake have a child together named Penny. Carey and Blake treat all three children the same. Yet when Carey dies without a will or trust, her family must rely on state law to determine who receives Carey’s assets. Everything that was owned solely by Carey is divided between Blake, Rose, and Penny. Although treated like a son, Whitley would be entitled to nothing. This may not be the outcome Carey would have desired. Without an estate plan, however, nothing more can be done. With a will or trust, you can control what happens to your money and property and who will benefit from your hard work, essentially eliminating the risk of regrettable results.

Another issue with relying on state law is that none of the transfers to your loved ones happen automatically. Your family must open a probate estate with the court and go through the process specified in state law before your property can transfer out of your name and into theirs. This process can be long and costly. It is also public. Many people would prefer that an inventory of their property and the details of their family life be kept out of the public eye. Perhaps the best way to keep your matters private is by creating and funding a revocable living trust while you are alive and have the legal capacity to do so.

Furthermore, if both parents of minor-aged children die without an estate plan, then the children are left without a legal guardian. Kids do not automatically go to a godparent or grandparent, even if that is what everyone knew the parents had intended. Instead, a court will appoint someone to be the children’s guardian. In such situations, the judge seeks to act in the children’s best interests and gathers information on the parents, the children, and the family circumstances. But the decision is up to the court; the judge, following the priority listed in the state’s law, may not choose the person that you, as their parent, would have chosen. If you had created a valid will during your lifetime, you would have been able to communicate to the judge whom you would have liked to appoint as guardian.

What if you and your spouse are separated?

State law decides what happens to your money and property if you are separated from your spouse when you die. In some states, the court ignores your separation and still considers you legally married. If the state intestacy law (which, again, applies if you die without a valid will) grants spouses a share of your property at your death, as most do, then your estranged spouse may be entitled to all or a portion of it when you die.

Also, some state laws or court orders prohibit you from disinheriting your spouse after you file for divorce but before it is finalized unless you have a prenuptial or postnuptial agreement. Without one of these agreements, you can try to omit your spouse from your will or your trust, but state law may kick in to require that a surviving spouse (who, again, is treated as being legally married to you) be given a share of what you own.

If you are separated from your spouse and your divorce is pending, talk with your divorce lawyer and an estate planning attorney about your options.

The best way to safeguard and pass along what you have worked so hard to build is to talk to a qualified estate planning attorney. Protect yourself, your family, and your money and property by contacting us today.

  1. David H. Lenok, The 50 Most Common Family Types in America, WealthManagement.com (July 20, 2016), http://www.wealthmanagement.com/high-net-worth/50-most-common-family-types-america. ↩︎
  2. Jannik Lindner, Remarriage Trends: Statistics Show Complex Dynamics for Couples Blending Families, Gitnux (July 17, 2024), https://gitnux.org/remarriage-statistics. ↩︎